Credit Management
How Credit Scores Work: FICO Factors and Ways to Improve
Learn how credit scores really work: the five FICO factors, the utilization math, what a low score costs you, and a simple 30-day plan to raise yours.

Your credit score is a three-digit grade, usually from 300 to 850, that predicts how likely you are to repay borrowed money on time. Lenders, landlords and insurers use it to decide whether to approve you and what to charge. It isn’t a measure of your income, your savings or your worth as a person. Instead, it only reflects what’s in your credit reports.
Five credit score facts to know before anything else
- Paying on time matters most. Payment history is the biggest part of a FICO score, about 35% for the typical person.
- How much of your limits you use comes next. Amounts owed, including your credit utilization, counts for about 30%.
- Those percentages are a general guide, not a formula. FICO says the importance of each category can vary from one person to another.
- You never need to pay interest to build credit. Instead, paying your full statement balance every month builds your score just as well.
- There’s no 30-day miracle. Some fixes, like lowering a reported balance, can show up within a billing cycle or two. But others, like building a long history, take years.
Keep those in mind, and the rest of this guide will make a lot more sense.
What you’ll learn
- What a credit score measures, and what it ignores completely
- The five ingredients of a FICO score and how much each one counts
- The simple math behind credit utilization, the fastest lever you can pull
- How much a lower score can cost you on a real car loan
- How to get your reports free, spot errors and dispute them
- A 30-day plan to start building or fixing your score
Table of contents
- What a credit score really is
- Credit reports: where your score comes from
- Score ranges, and why you have many scores
- The five ingredients of a FICO score
- Credit utilization: the lever you control fastest
- Hard pulls, soft pulls and rate shopping
- What your score really costs you
- How to check your reports and fix errors
- Building credit from scratch or starting over
- Your 30-day credit action plan
- Common mistakes that drag scores down
- Credit score myths that won’t die
- Bottom line
- FAQ
What a credit score really is
A credit score is a number that estimates how likely you are to pay back a loan on time. The Consumer Financial Protection Bureau (CFPB), the federal agency that watches over consumer lending, calls it “a prediction of your credit behavior.” That’s the whole job. In other words, it’s a forecast, not a report card on your character.
Most scores run from 300 to 850. A higher number tells a lender you look less risky. A lower number tells them the opposite, so they either say no or charge you more to cover the risk.
Lenders aren’t the only ones who look. The CFPB notes that landlords, insurance companies and even cell phone and utility companies may check your credit. Some employers can check your credit report too, but only with your permission.
What your credit score ignores
This part surprises a lot of people. Your credit score doesn’t know your income. It also doesn’t know how much you have in savings or in your 401(k). It doesn’t care if you own your home outright or pay your rent early every month (unless that rent gets reported, which we’ll get to later).
Instead, the score only sees what shows up on your credit report. In other words, it’s really a measure of how you’ve handled borrowed money. For example, someone earning $40,000 a year who pays two credit cards on time can have a higher score than someone earning $400,000 who missed a few payments.
FICO, the company behind the most widely used score, lists what it leaves out on its “What’s not in my FICO Scores” page. That list includes your race, religion, sex, marital status, age, salary, job and where you live. Age can still show up indirectly, though, since older people tend to have older accounts. You’ll see that in the data later on.
Why your credit score matters so much
A score changes three things for you: whether you get approved, what interest rate you pay and how much you’re asked to put down as a deposit. In fact, a few points can be the difference between two pricing tiers. Over a five-year car loan or a 30-year mortgage, that gap adds up to thousands of dollars.
It also affects people more often than you’d think. The Federal Reserve’s latest survey of household finances found that 33% of adults applied for some kind of credit in 2025. About one-third of those applicants were either turned down or approved for less than they asked for.
Credit reports: where your credit score comes from
Your score is built from your credit report, so it helps to know what’s in there. A credit report is a record of how you’ve used credit. Three big companies, called credit bureaus, keep these records: Equifax, Experian and TransUnion.
Banks, card companies and other lenders send information about your accounts to the bureaus, usually once a month. These lenders are called “furnishers” because they furnish the data. Here’s a catch, though. The CFPB points out that lenders aren’t required to report to every bureau. So your three reports can look a little different from each other, and your scores can too.
What’s on your report
According to the CFPB, a typical credit report includes five kinds of information:
- Personal details. Your name, current and past addresses, birth date, Social Security number and phone numbers.
- Credit accounts. Each card and loan, with its type, credit limit, balance, payment history, and the dates it was opened or closed.
- Collection items. Debts that were sent to a collection agency, plus certain overdue child support.
- Public records. Items like bankruptcies, foreclosures, liens and court judgments.
- Inquiries. A list of companies that have pulled your report.
Your personal details don’t affect your score. They’re there so the bureau can match the right file to the right person. That said, a wrong address or an unfamiliar name can be an early clue that something’s off, like a mixed-up file or identity theft.
How long bad news sticks around
Negative items don’t stay forever. The CFPB says most negative information can be reported for seven years, and a bankruptcy can stay for up to 10 years. A late payment from five years ago still shows up, but it counts for much less than a late payment from last month. Time really does heal here.
Medical debt has its own rules now. In 2022 and 2023, the three bureaus made a few changes. First, they removed paid medical collections. Second, they now wait a full year before showing unpaid ones. Finally, they dropped medical collections that started under $500. They said close to 70% of medical collection accounts were gone from credit files after those changes.
You may also have heard that medical bills were banned from credit reports. The CFPB did finalize a rule like that in January 2025. But at the joint request of the CFPB and the groups challenging it, a federal court in Texas vacated the rule on July 11, 2025. The judge found the CFPB had gone beyond its authority under the Fair Credit Reporting Act (Ballard Spahr’s Consumer Finance Monitor summarizes the ruling). So that federal ban never took effect.
The bureaus’ own 2022 and 2023 changes described above weren’t part of that rule, so the ruling didn’t undo them. Some states have passed their own limits on medical debt reporting. But how far those laws reach is disputed. In October 2025, the CFPB published an interpretive rule saying federal law generally overrides state credit reporting laws. The same rule notes that it isn’t legally binding and that courts have the final say. If a medical bill shows up on your report, check your state attorney general’s website, and dispute anything that’s paid, under $500 or less than a year old.
Buy now, pay later: does it count?
“Pay in 4” plans are everywhere at checkout, so it’s fair to ask what they do to your score. The CFPB says most buy now, pay later (BNPL) lenders don’t report your payment history to the big credit bureaus, so on-time payments usually won’t help. Applying usually doesn’t cause a hard inquiry either. The risk runs one way, though: if an unpaid BNPL balance goes to a debt collector, the collector may report it, and that can hurt.
That picture is slowly changing. In April 2025, Affirm said it would report all of its pay-over-time loans to TransUnion, starting with loans made on May 1, 2025. When Affirm made that announcement, it said those loans wouldn’t be visible to lenders or counted in traditional scores. In June 2025, FICO announced its first scores that include BNPL data, offered alongside its existing scores. Lenders decide which score they use, so a newer model existing doesn’t mean your lender uses it.
Before you click “Pay in 4,” run through this quick check:
- Can you cover every installment from money you already have? If not, the plan is just a short loan you can’t afford.
- Is it a longer monthly plan? The CFPB notes that bigger, longer-term BNPL loans may involve a hard inquiry and may report your payments, so read the terms first.
- How many plans are open right now? Several small plans due on different dates are easy to lose track of, and a missed one can lead to fees or collections.
Credit score ranges, and why you have many scores
So what counts as a good score? Chase’s credit education page lays out the standard FICO ranges. Here’s how they line up:
| FICO score | Label | What it usually means for you |
|---|---|---|
| 800 to 850 | Exceptional | The best rates and easy approvals |
| 740 to 799 | Very good | Near-best rates on most loans |
| 670 to 739 | Good | Approved by most lenders at fair rates |
| 580 to 669 | Fair | Approvals possible, but at higher rates |
| 300 to 579 | Poor | Many denials; secured cards and deposits likely |
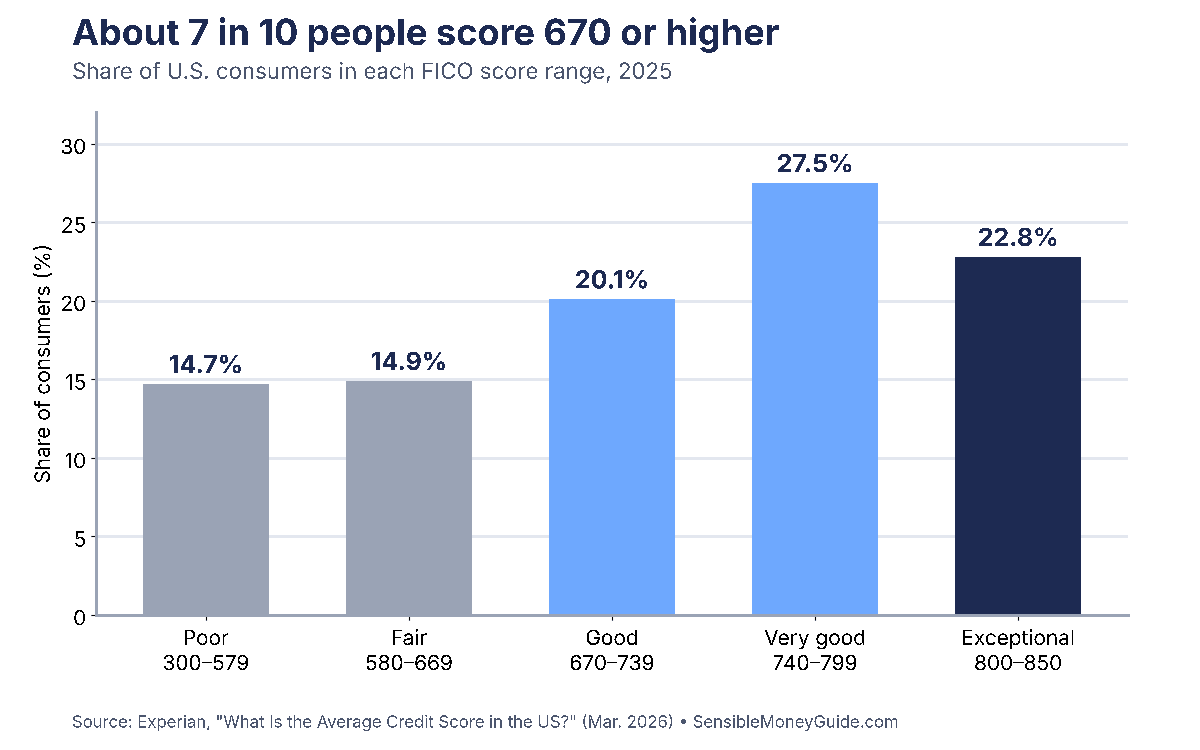
The average American sits right in the “good” zone. Experian reports that the national average FICO score was 713 in 2025, down two points from 715 in 2024. Experian called it the first yearly drop in the national average since 2013.
About 70% of consumers have a score of 670 or higher. On the other end, nearly 15% are in the “poor” range. The chart below shows how people are spread across the five bands.
Wait, I have more than one credit score?
Yes, and lots of them. The CFPB explains that your score depends on which bureau’s data is used, which scoring model runs the math, and the day it’s calculated. Change any one of those and the number can shift.
The two big scoring brands are FICO and VantageScore. Both use the 300-to-850 range and both look at your credit report data. They weigh things a little differently, though, so they rarely match exactly.
Each brand also has several versions. Chase notes that FICO Score 8 is the most widely used. However, mortgage lenders have long used older versions, like FICO Score 2 from Experian and FICO Score 4 from TransUnion.
Which score will a mortgage lender use?
That’s starting to change in the mortgage world. In April 2026, the Federal Housing Finance Agency (FHFA), which oversees Fannie Mae and Freddie Mac, announced that the two companies would accept VantageScore 4.0, with FICO Score 10T to follow. Since then, things have moved. FHFA’s credit score page says all approved lenders could use VantageScore 4.0 starting September 9, 2026. On September 30, Fannie Mae and Freddie Mac published changes to their upfront fees so the fees match across the two models. Older “Classic FICO” scores are still accepted, and FICO 10T isn’t yet eligible for delivery.
FHA loans are on a different timeline. HUD’s Mortgagee Letter 2026-11 (October 8, 2026) adds FICO 10T and VantageScore 4.0 alongside Classic FICO. It applies to FHA case numbers assigned on or after January 1, 2027. FHA still requires a report from all three bureaus. Here’s where things stand as of October 27, 2026:
| Loan type | Scores lenders can use now | What’s still pending |
|---|---|---|
| Conventional loans sold to Fannie Mae or Freddie Mac | Classic FICO or VantageScore 4.0 (the lender picks one model for all borrowers on the loan) | FICO 10T; no retirement date set for Classic FICO |
| FHA loans | Classic FICO | FICO 10T and VantageScore 4.0 for case numbers assigned on or after Jan. 1, 2027 |
Example: how an FHA lender turns six scores into one
The FHA letter spells out how a lender picks the score that counts. For each scoring model, the lender takes the middle of your three bureau scores (or the lower of two). If it submits more than one model, each borrower gets the lowest of those picks. Then the loan’s “minimum decision credit score” is the lowest borrower score on the application. Here’s a hypothetical couple applying together in 2027:
| Borrower (hypothetical) | Classic FICO scores → middle | VantageScore 4.0 scores → middle |
|---|---|---|
| Borrower A | 688, 702, 715 → 702 | 695, 710, 720 → 710 |
| Borrower B | 655, 660, 671 → 660 | 664, 668, 690 → 668 |
- Borrower A’s score is 702, the lower of 702 and 710.
- Borrower B’s score is 660, the lower of 660 and 668.
- The loan’s decision score is 660, the lower of the two borrowers. If the lender had submitted only VantageScore 4.0, it would have been 668.
What the example shows
Two lessons jump out. First, the co-borrower with the weaker credit sets the number for the whole loan. So it can pay for that person to work on their score before you apply. Second, adding a second scoring model can never raise the decision score under this rule; it can only keep it the same or lower it. FHA’s cutoffs didn’t change. Under HUD’s long-standing rules, a decision score of 580 or higher qualifies for maximum financing. A score of 500 to 579 caps the loan at 90% of the home’s value, so you need at least 10% down. Below 500 isn’t eligible. Our guide to how much you need for a down payment walks through the cash side.
What does this mean for you? Don’t panic if the score in your banking app is 20 points off from the one your lender sees. Watch the trend instead. If your free score is climbing over time, the ones lenders use are usually climbing too, because they’re built from the same habits. They don’t always move in lockstep, though, because each scoring model and each bureau’s data can differ.
Pro tip: Pick one free score source and stick with it. That’s because checking the same score, from the same bureau, every month gives you an apples-to-apples trend line. Bouncing between apps, on the other hand, just adds noise.
The five ingredients of a FICO score
FICO doesn’t publish its exact formula. It does publish the recipe, though. On its “What’s in your credit score?” page, FICO breaks the score into five categories and shows roughly how much each one counts for the general population:
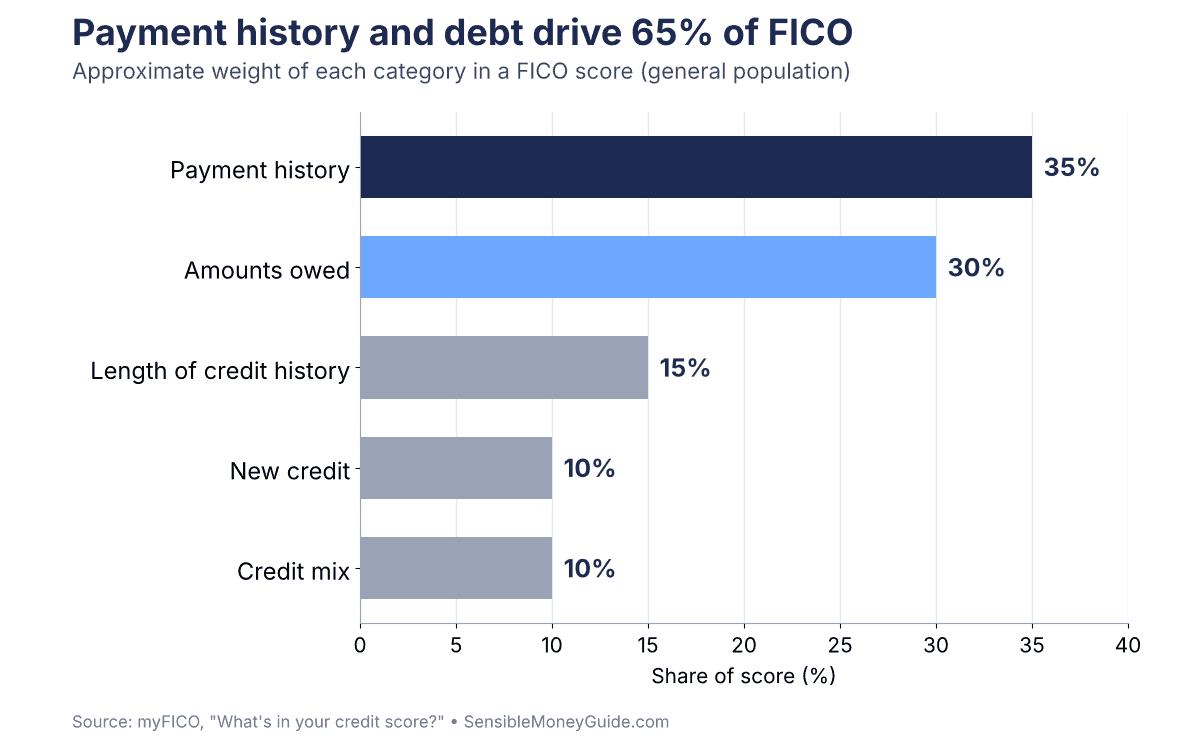
Two things jump out. First, payment history and amounts owed make up 65% of the score together. If you get those two right, you’ve done most of the work. Second, the last three factors are small. That’s why chasing a “perfect mix” of accounts is usually a waste of energy.
One caution: these percentages are averages, not a fixed formula for you. FICO itself says “the importance of these categories may vary from one person to another.” Someone with a brand-new file, for example, is scored differently than someone with 20 years of history. VantageScore, the other big scoring brand, weighs things in its own way too.
If you’d like a quick visual walk-through before we go factor by factor, this short video from Two Cents, a personal finance series from PBS, covers the same ground.
1. Payment history (about 35%)
This is the big one. It answers a simple question: do you pay as agreed? So each on-time payment adds to a positive record. Experian explains that lenders generally report a payment as late once it’s 30 days past due, and the mark can stay on your report for seven years. (Federal student loans aren’t reported late until 90 days.)
FICO notes that a few late payments won’t automatically ruin your score. It also says a spotless record doesn’t guarantee a perfect score. How late you were, how recent it was and how often it happened all matter. For example, a single 30-day late payment from four years ago hurts far less than a 90-day late payment from two months ago.
Collections, charge-offs and bankruptcies also live in this category. They’re the most damaging items, which is why the most important habit in this whole guide is this one: never let a bill go 30 days past due.
2. Amounts owed (about 30%)
This one looks at how much you owe and, more importantly, how much of your available credit you’re using. That share is called your credit utilization ratio. For example, if you have a $5,000 limit and a $2,500 balance, your utilization is 50%.
FICO explains that using a big chunk of your limits can suggest you’re stretched thin. This factor matters so much, and moves so fast, that it gets its own section next.
3. Length of credit history (about 15%)
This factor looks at how long you’ve had credit. FICO considers the age of your oldest account, the age of your newest one and the average age of all of them. It also checks how long it’s been since you used certain accounts.
A longer history generally helps, but it isn’t required for a good score. You can’t speed this one up. You can avoid hurting it, though, by keeping your oldest no-fee card open and using it now and then.
4. New credit (about 10%)
Opening several accounts in a short time looks risky, especially if your credit history is short. Each application for a loan or card usually adds a “hard inquiry” to your report. FICO only counts inquiries from the last 12 months, even though they stay on your report for two years.
5. Credit mix (about 10%)
This factor looks at the types of credit you have. That can include credit cards, store cards, installment loans (like a car loan, where you pay a fixed amount each month), and mortgages. FICO says plainly that you don’t need one of each. So never take out a loan just to improve your mix. The interest will cost you far more than the few points could ever be worth.
Keep in mind that these percentages are averages. FICO says the importance of each category can vary from one person to another. For example, a new account may matter more for someone with a thin file than for someone with 20 years of history.
Credit utilization: the lever you control fastest
If you want to raise your score soon, utilization is where to look. Here’s why: your utilization is figured from the balances your card companies report, and those usually update every month. Pay your balances down and your score can improve once the lower numbers get reported. A late payment, on the other hand, sticks around for years.
How to figure out your utilization
The math is simple. First, add up all your credit card balances. Next, add up all your credit limits. Then divide the first number by the second. Finally, do the same for each card by itself, because scoring models look at both.
Worked example 1: Finding your ratio
Say you have three cards:
- Card A: $1,200 balance on a $3,000 limit (40%)
- Card B: $1,800 balance on a $5,000 limit (36%)
- Card C: $0 balance on a $2,000 limit (0%)
Your total is $3,000 in balances on $10,000 in limits. That’s an overall utilization of 30%. Now say you send $2,000 to Cards A and B before their statements close. Then your reported balance drops to $1,000, and your utilization falls to 10%.
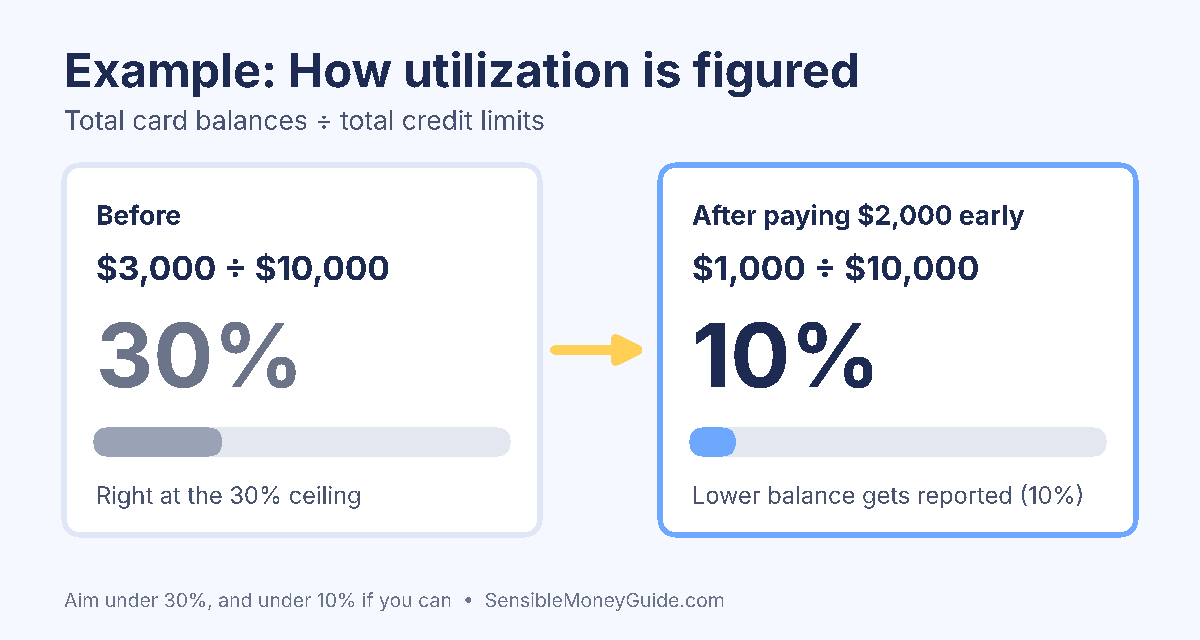
How low should you go? Bank of America’s Better Money Habits site suggests keeping utilization below 30%. NerdWallet gives the same 30% guideline but adds that “less is better.” It also notes that people with the best scores often keep utilization in the single digits.
So think of 30% as a ceiling, not a target. Under 10% is even better. But going all the way to zero on every card isn’t the goal either. A small balance that you pay in full each month shows that you use credit and handle it well.
The statement date trick
Here’s something a lot of people miss. Your card company usually reports your balance to the bureaus around your statement closing date, not your due date. So even if you pay in full every month, a big balance on the statement can make your utilization look high. NerdWallet makes the same point: paying during the month makes it more likely a lower balance gets reported.
The fix is easy. Make a payment a few days before your statement closes. You’ll still pay the rest by the due date, but the bureaus see a lower number. In fact, it’s one of the few score moves that costs you nothing at all.
Don’t confuse these two things: letting a small balance show up on your statement is fine and can even help. However, carrying a balance past the due date is what costs you interest, and it doesn’t help your score. So pay the full statement balance by the due date every month.
“The reason is simply because the higher your balances are, the greater risk you’ll default.”
Rod Griffin, senior director of consumer education at Experian, explaining to CNBC Make It why high utilization lowers scores
Worked example 2: Closing a card
Let’s go back to the three cards from Example 1, with $3,000 in total balances. Now say you close Card C, the one with a $2,000 limit and no balance, because you never use it.
Your limits drop from $10,000 to $8,000. But your balances are still $3,000. As a result, your utilization jumps from 30% to 37.5%, even though you didn’t spend a single extra dollar.
Bankrate explains that this is the main way closing a card can hurt you. It also notes that a closed account can stay on your report for up to 10 years, so the hit to your credit age comes slowly. So if a card has no annual fee, keeping it open and using it for a small bill now and then is usually the smarter play.
Watch out: If an old card charges an annual fee you don’t want to pay, call the issuer before you close it. Some issuers will let you switch to a no-fee card from the same company, which keeps the account and its credit limit alive.
Hard pulls, soft pulls and rate shopping
Every time someone looks at your credit, it’s called an inquiry. There are two kinds, and only one of them can touch your score.
- Soft inquiries happen when you check your own credit, when a card company sends you a pre-approved offer, or when a current lender reviews your account. They don’t affect your score at all. So check your own score as often as you like.
- Hard inquiries happen when you apply for new credit, like a credit card, car loan or mortgage, and the lender pulls your report to make a decision. These can lower your score a little.
How little? FICO says that for most people, one extra hard inquiry takes less than five points off their score. Hard inquiries stay on your report for up to two years, but FICO scores only count them for the first 12 months.
Shopping for the best rate won’t wreck your credit score
Here’s a fear that keeps people from shopping around: “If five lenders check my credit, I’ll get five dings.” But for the biggest loans, that’s not how it works.
FICO treats several inquiries for the same kind of loan as one inquiry, as long as they happen close together. This “rate shopping” rule covers mortgages, auto loans and student loans. Older FICO versions use a 14-day window. Newer versions, however, use 45 days. FICO also ignores these rate-shopping inquiries for the first 30 days after they happen.
Since you can’t always know which version a lender uses, the safe move is to do all your loan shopping within about two weeks. That way you’re covered no matter what.
But credit cards don’t get this break. FICO says several card applications in a row can look like you’re hunting for a lot of new credit at once. So each card application usually counts as its own inquiry.
Pro tip: Planning to buy a home or car in the next six months? Hold off on opening new cards until after you close on the loan. Even a store card at checkout adds a hard inquiry and a new, young account.
What your credit score really costs you
A credit score can feel abstract until you see it in dollars. Car loans make it easy to see, because lenders price them in clear tiers.
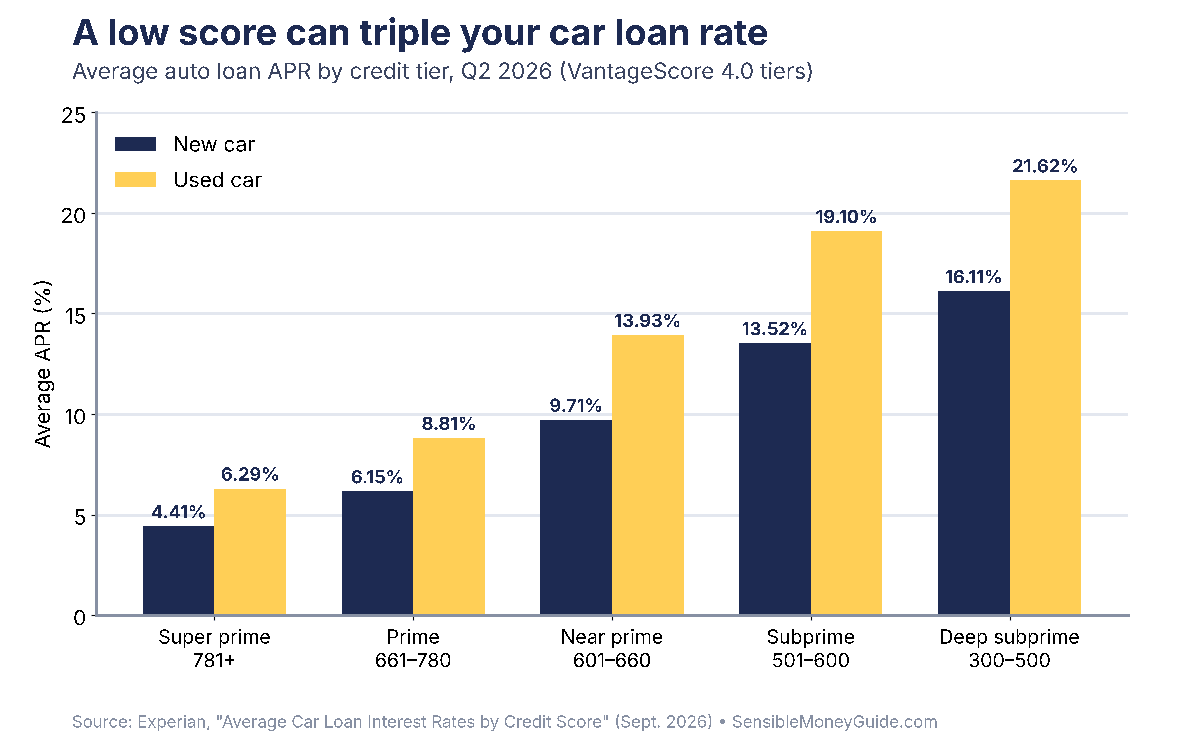
Experian tracks average auto loan rates by credit tier. Its numbers for the second quarter of 2026 show a wide gap between the top and bottom groups. (One note: Experian groups these by VantageScore 4.0, so the tier cutoffs are a little different from the FICO bands above.)
Worked example 3: The same car, five different prices
Let’s say you borrow $30,000 for a new car over five years (60 months). Using Experian’s average new-car rates, here’s what the monthly payment and total interest look like for each tier. We used the standard loan payment formula to run the numbers.
| Credit tier | Average APR | Monthly payment | Total interest over 5 years |
|---|---|---|---|
| Super prime (781+) | 4.41% | $558 | $3,484 |
| Prime (661 to 780) | 6.15% | $582 | $4,925 |
| Near prime (601 to 660) | 9.71% | $633 | $7,988 |
| Subprime (501 to 600) | 13.52% | $691 | $11,436 |
| Deep subprime (300 to 500) | 16.11% | $731 | $13,878 |
Same car. Same price. The person in the lowest tier pays about $10,400 more in interest than the person at the top. Even moving up one step, from near prime to prime, saves about $3,060 on this loan.
Now picture a hypothetical buyer, Nicole, at a car dealership. If she’s buying a $20,000 used car, the gap is just as sharp. At Experian’s average used-car rate for super prime borrowers (6.29%), her payment would be about $389 a month. But at the subprime average (19.10%), it would be about $520. Over five years, that’s roughly $7,830 in extra interest.
It’s not just loans
The cost shows up in other places too. For example, a lower score can mean a security deposit on a new apartment or utility account. The National Association of Insurance Commissioners says most car and home insurers use credit-based insurance scores in states that allow it, though state laws limit how they’re used. And the Federal Reserve found that one in three people who applied for credit in 2025 were denied or approved for less than they wanted.
None of this means you should obsess over every point. Once you’re in the upper tiers, a few more points rarely change your price. Instead, the big money is in moving up from “fair” to “good,” or from “good” to “very good.”
How to check your reports and fix errors
You can’t fix what you can’t see. Luckily, checking your credit reports is free, and it doesn’t hurt your score.
Get your free reports
Federal law gives you a free credit report from each of the three bureaus. Better yet, the bureaus have made free weekly reports permanent. The Federal Trade Commission (FTC) says the only website authorized to provide them is AnnualCreditReport.com. You can also order by phone at 1-877-322-8228.
Also, watch out for look-alike sites. The FTC warns that some websites with similar names try to sell you paid services or collect your personal information. AnnualCreditReport.com won’t email you asking for your Social Security number.
Your free reports don’t always include a score. That’s fine, because many banks and card companies now show a free score in their apps. The report is the more important document anyway, because it’s where errors hide.
Errors are more common than you’d think
An FTC study found that about one in five people had an error on at least one of their three reports. About 5% had errors serious enough that they could end up paying more for things like car loans. That study is from 2013, but it’s still the largest federal look at the issue, and it’s a good reason to check.
Here’s what to look for when you read your report:
- Accounts you don’t recognize (a possible sign of identity theft)
- Late payments you know you made on time
- The same debt listed twice, such as by the original lender and a collector
- Wrong credit limits, which can make your utilization look higher
- Negative items older than the seven-year limit
- Paid medical collections, or ones that started under $500
How to dispute a mistake
The CFPB recommends a two-part approach. Start by disputing with the credit bureau that shows the error. Then also dispute with the company that reported it. Also, do both in writing.
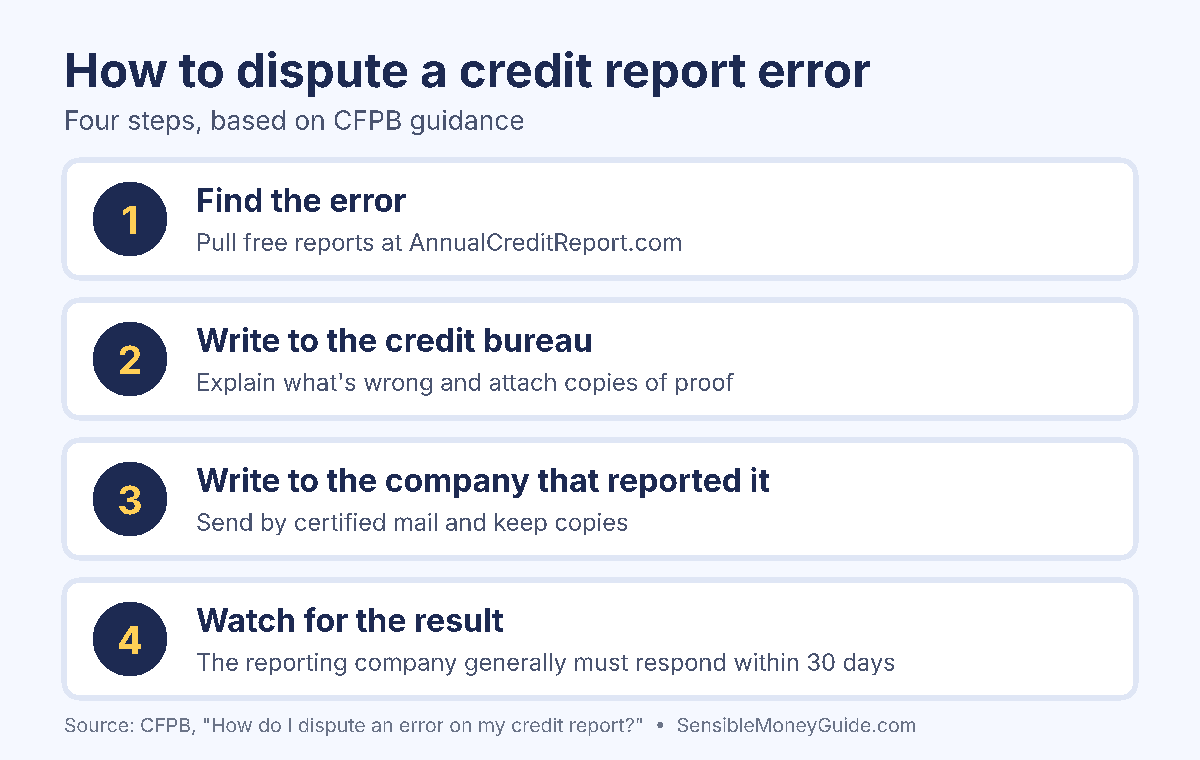
Your dispute letter should include your name, address and phone number, the account number, a clear explanation of what’s wrong, and a request to fix or remove it. Include copies (never originals) of any proof, like a bank statement showing an on-time payment. The CFPB says you can send it by certified mail with a return receipt, and it suggests certified mail for the company that reported the item. Also, keep copies of everything.
The company that supplied the information generally has to investigate and respond within 30 days. If it can’t verify the item or finds it’s wrong, it has to correct it or remove it and tell the bureaus. If it says the item is correct, you can ask the bureau to add a short statement of your side to your file.
Lock the door with a free credit freeze
A credit freeze stops new lenders from pulling your report, which makes it much harder for a thief to open accounts in your name. The FTC says freezes are free and won’t lower your score. Even so, you can still use your current cards. You have to contact all three bureaus to freeze, and you can lift it for free when you want to apply for something.
A fraud alert is a lighter option. It asks lenders to verify your identity before opening an account. A basic alert lasts one year, and identity theft victims can get an extended alert that lasts seven years.
Building credit from scratch or starting over
Not everyone has a score to improve. In fact, some people don’t have one at all yet. The CFPB calls these people “credit invisible,” meaning they have no credit record at the bureaus.
The CFPB once estimated that about 26 million adults were credit invisible. In a 2025 update, it corrected that figure and said that by the end of 2020, about 2.7% of adults, or around 7 million people, were credit invisible. Another 9.8% had a credit record that was too thin or too old to produce a score.
If that’s you, here’s what to know: FICO needs at least one account that’s been open and reporting to the bureaus for six months or more before it can give you a score, according to Capital One. VantageScore may be able to score you sooner. Either way, the clock starts the day you open your first account. Our first-year plan for building credit from scratch lays out the order to do things in.
Good ways to get started
- A secured credit card. You put down a cash deposit, often a few hundred dollars, and that usually becomes your credit limit. Then you use it like a normal card. Some issuers review your account over time and may move you to a regular card and return your deposit.
- Become an authorized user. A parent, partner or trusted friend adds you to their card. Capital One notes that their good habits can help your credit, but their missed payments can hurt it too. So only do this with someone who pays on time and keeps balances low.
- A credit-builder loan. These are small loans, generally $300 to $1,000, according to Capital One, which cites the CFPB. Unlike a normal loan, you make the payments first and get the money at the end. Along the way, you build a record of on-time payments.
- Rent reporting. Some landlords and services report your rent payments to the bureaus. If yours doesn’t, it’s worth asking.
The long view: your credit score grows with time
Because length of history counts, scores tend to rise with age. Experian’s 2025 data shows a clear pattern. The average FICO score for Gen Z is 678, while baby boomers average 747.
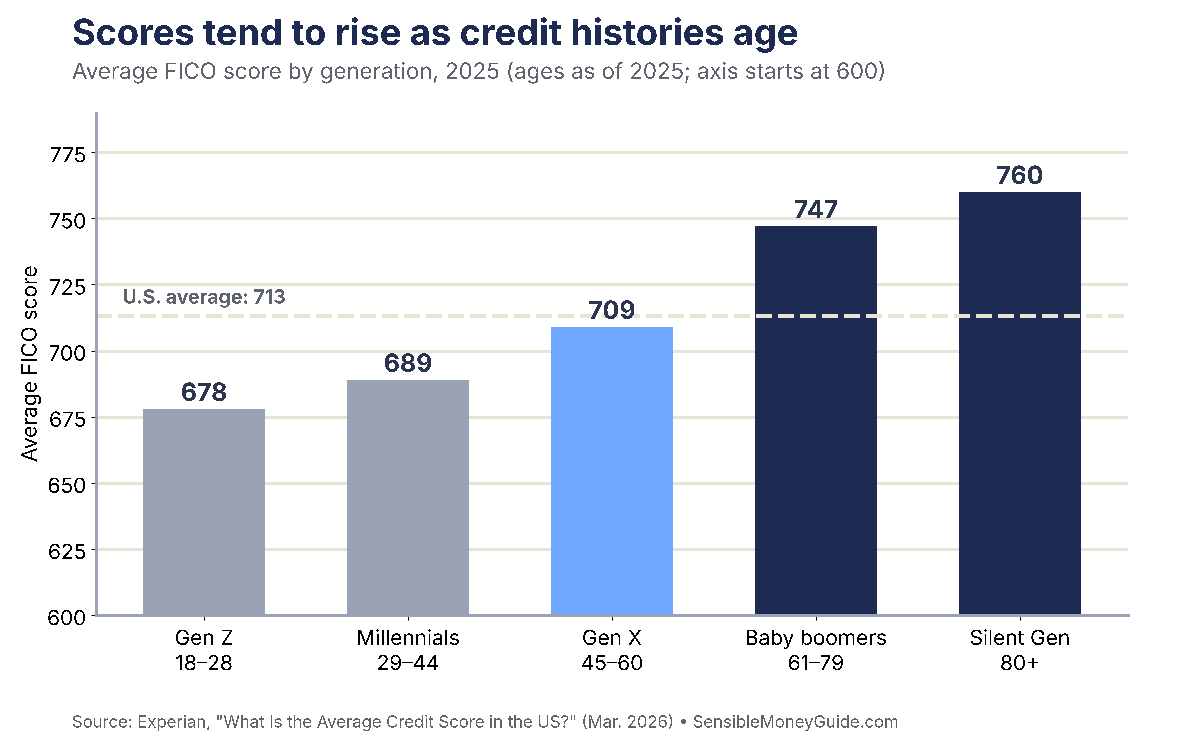
That’s encouraging if you’re young or starting over. A lot of what separates a 680 from a 750 is simply years of steady, boring, on-time payments.
Rebuilding after a rough patch
If you’ve had late payments, a collection or a bankruptcy, rebuilding takes patience. Capital One notes that serious credit problems can take years to repair. The steps are the same as building from scratch: pay every bill on time from now on, keep balances low and avoid applying for lots of new credit.
Negative items lose their sting as they age, and most fall off after seven years. Older problems count for less than recent ones, so every month of clean history helps.
Do you even need a credit score?
Not every money expert thinks you should care. Ramsey Solutions, the company behind radio host Dave Ramsey, calls the credit score an “I love debt score.” In its view, the score mainly measures how much you borrow, not how well you handle money. Ramsey’s advice is to pay off debt, stop borrowing and live without a score. It points out that some lenders will approve a mortgage through “manual underwriting,” where a person reviews your full financial picture instead of relying on a score.
Most other experts see it differently. Bank of America, NerdWallet and Bankrate all treat a good score as a tool worth keeping, mainly because it’s checked in so many places. Landlords, insurers and phone companies may look at your credit even if you never borrow a dime. And manual underwriting isn’t offered everywhere and can take more paperwork.
Here’s a fair middle ground. After all, you don’t need debt to have a good score. One or two no-fee cards, used for small purchases and paid in full every month, can build an excellent score without costing you a penny in interest.
Your 30-day credit action plan
Knowing how scores work is half the battle. Here’s how to put it to use over the next month. None of these steps cost money.
A quick reality check: nobody can promise your score will rise by a set amount in 30 days. Results depend on when your card companies report to the bureaus, what’s already in your file and which scoring model a lender uses. What a month can do is fix errors, stop new damage and set up habits that keep paying off.
- Pull all three reports (day 1). Go to AnnualCreditReport.com and download your Equifax, Experian and TransUnion reports. Then save them as PDFs.
- Read every account line (days 2 and 3). Check names, balances, limits and payment history. Then mark anything that looks wrong or unfamiliar.
- Dispute errors (by day 7). Write to the bureau and the company that reported the item. Send by certified mail and keep copies.
- Set up autopay for at least the minimum (by day 7). Do this on every card and loan. It’s your safety net against a forgotten due date, the costliest mistake there is.
Days 10 to 30: lower balances and protect your credit score
- Find your statement closing dates (by day 10). Log in to each card and write down when the statement closes. Set a phone reminder three days before each one.
- Figure out your utilization (by day 10). Add up balances and limits, overall and per card. Use the math from Worked Example 1.
- Pay balances down before they report (days 10 to 30). Aim to get every card under 30%, and under 10% if you can. Start with the card that has the highest percentage.
- Keep your oldest no-fee card active (ongoing). Put one small recurring bill on it, like a streaming service, and let autopay cover it in full.
- Pause new applications (ongoing). Unless you truly need it, skip new cards for now. Store card offers at checkout also count.
- Freeze your credit (by day 30). Place free freezes at all three bureaus. Lift one only when you’re ready to apply for something.
Then check your free score once a month. You’re looking for a steady trend up, not overnight miracles.
Which moves pay off, and how fast
Not every step works on the same clock. This table sums up what each habit does, based on how FICO weighs the factors and how long items stay on your report.
| Move | Factor it affects | How fast it can show up |
|---|---|---|
| Pay down card balances | Amounts owed (about 30%) | Once lower balances are reported, often the next statement |
| Fix an error on your report | Depends on the error | After the dispute is resolved, generally about a month |
| Pay every bill on time | Payment history (about 35%) | Builds slowly, month after month |
| Stop applying for new credit | New credit (about 10%) | Inquiries stop counting after 12 months |
| Keep old accounts open | Length of history (about 15%) | Pays off over years |
| Wait out old negative items | Payment history | Most drop off after seven years |
Notice the pattern. The quick wins come from balances and errors. But the big, lasting gains come from time and on-time payments. Do the quick ones this month, and let the slow ones work in the background.
Common mistakes that drag scores down
Most credit damage comes from a handful of everyday slip-ups. Here are the ones to watch for.
Letting a bill slide past 30 days
A payment that’s a few days late usually means a late fee. Once it hits 30 days past due, it can be reported to the bureaus and stay for seven years. If you’re ever going to miss, call the lender before the 30-day mark and ask about options.
Maxing out a card, even if you pay it off
If your statement shows a $2,800 balance on a $3,000 limit, the bureaus may see 93% utilization. It doesn’t matter that you pay it all off two weeks later. So pay before the statement closes.
Closing your oldest card
As Worked Example 2 showed, closing a card can push your utilization up right away. Over time, it can also shorten your credit history. Ask for a no-fee version instead.
Opening store cards for a one-time discount
Saving 15% on one purchase can cost you a hard inquiry and a new account, right before you need a car loan. The trade-off is rarely worth it.
Ignoring small collections
For example, a forgotten $60 bill from an old phone company can turn into a collection account. Read your reports and handle small debts before they’re sent to a collector. If one is already there, it’s worth disputing if it’s wrong, or paying if it’s right.
Co-signing without thinking it through
When you co-sign, the loan shows up on your report too. If the other person pays late, your score takes the hit. So only co-sign if you could afford to make every payment yourself.
Paying for a credit score you can get free
Many banks and card issuers show free scores in their apps, and your reports are free every week. So be wary of any service that charges you just to see your own information.
Credit score myths that won’t die
Credit scores attract a lot of folklore. Here’s what the scoring companies and federal agencies actually say.
Myth: Checking your own score lowers it.
Fact: Checking your own credit is a soft inquiry. It never affects your score. Check as often as you like.
Myth: You have to carry a balance to build credit.
Fact: Paying in full every month builds credit just as well, and you pay zero interest. What’s reported is your balance on the statement, not whether you paid interest.
Myth: Your income affects your score.
Fact: FICO says salary, job and employer are not part of its scores. Lenders may ask about income on an application, but it isn’t in the score.
Myth: Closing old cards helps your score.
Fact: Closing a card usually lowers your available credit, which can push your utilization up. It can also shorten your history over time.
Myth: Shopping for a mortgage or car loan will crush your score.
Fact: FICO counts multiple mortgage, auto or student loan inquiries within a short window as one. So shop around within about two weeks.
Myth: Paying off a collection removes it right away.
Fact: Most negative items can be reported for up to seven years whether they’re paid or not. Paid medical collections are an exception; the bureaus now remove those.
Myth: Everyone has just one credit score.
Fact: You have many, based on different bureaus, models and versions. So focus on the trend, not one exact number.
“It is a challenging time, but it’s important for people to understand that they have more power over their money and over their interest rates than they think they do.”
Matt Schulz, chief consumer finance analyst at LendingTree, speaking to CNN in January 2026
Bottom line
- A credit score predicts how likely you are to repay on time. It doesn’t measure income, savings or worth as a person.
- Your score comes from your credit reports at Equifax, Experian and TransUnion, and those reports can differ.
- Payment history (about 35%) and amounts owed (about 30%) make up most of a FICO score.
- Keep credit card utilization under 30%, and under 10% if you can. Pay before your statement closes.
- Rate shopping for a mortgage, auto or student loan within a short window counts as one inquiry.
- A lower score can cost thousands. On a $30,000 car loan, the top tier pays about $10,400 less interest than the bottom.
- Check your reports free every week at AnnualCreditReport.com and dispute errors in writing.
- You don’t need to carry debt or pay interest to build an excellent score.
FAQ
What is a good credit score?
On the FICO scale, 670 to 739 is considered good, 740 to 799 is very good and 800 or higher is exceptional. The national average was 713 in 2025, according to Experian. Lenders price loans in tiers, so once you reach the top tier (for Experian’s auto loan data, that starts at 781), extra points don’t lower your rate.
How fast can I raise my credit score?
It depends on what’s holding it back. If high card balances are the problem, paying them down can help once the lower balances are reported, often within a month or two. If late payments or collections are the problem, it takes longer, since those can stay for up to seven years and fade slowly.
Does checking my credit score hurt it?
No. Checking your own score or report is a soft inquiry and has no effect. Only hard inquiries, which happen when you apply for new credit, can lower your score, and usually by less than five points.
Why is my credit score different on different apps?
Each app may use a different bureau’s data, a different scoring model (FICO or VantageScore) or a different version. Scores also change daily as new data comes in. So track one source over time rather than comparing numbers across apps.
How long do late payments stay on my credit report?
Most negative information, including late payments, can be reported for up to seven years. Bankruptcies can stay for up to 10 years. However, the impact shrinks as the item gets older, especially if your recent history is clean.
Will paying off a collection raise my credit score?
It depends on the scoring model the lender uses. Experian explains that FICO Scores 9 and 10 and VantageScore 3.0 and 4.0 ignore paid collections, while the widely used FICO Score 8 still counts them. Either way, paying it off stops further collection efforts, and paid medical collections are removed from reports entirely.
How do I build credit with no credit history?
Start with a secured credit card, a credit-builder loan or by becoming an authorized user on a trusted person’s card. FICO needs at least one account open for six months before it can score you. Then use the account lightly and pay on time every month.
Does a credit freeze hurt my score?
No. The FTC says freezes are free and don’t affect your score. You can still use your existing cards, and you can lift the freeze for free when you want to apply for new credit.
Does buy now, pay later affect my credit score?
Usually not directly, because most BNPL lenders don’t report on-time payments to the bureaus, according to the CFPB. But an unpaid plan sent to collections can be reported and can hurt your score. Some providers, like Affirm, now report loans to a bureau, and FICO has announced scores that can use BNPL data, so this is changing.
Will my mortgage lender use FICO or VantageScore?
It depends on the loan. Since September 2026, lenders selling loans to Fannie Mae or Freddie Mac can choose Classic FICO or VantageScore 4.0. FHA loans use Classic FICO for now, with FICO 10T and VantageScore 4.0 allowed for case numbers assigned on or after January 1, 2027. Ask your lender which one it pulls.
Try this next
Set aside 20 minutes this week, go to AnnualCreditReport.com and download your three free credit reports. Then read each account line and circle anything that doesn’t look right. That one step shows you exactly what lenders see, and it’s the foundation for everything else in this guide.
While you’re at it, it’s a good time to make sure your money plan supports your credit goals. Our guide on how to make a budget that actually works can help you find room to pay balances down, and our emergency fund guide shows how a cash cushion keeps a surprise bill from turning into a late payment.
About this guide
Published by Daniel Brienza, founder and editor of Sensible Money Guide (B.S. in Business Administration, University of South Florida). This guide was researched and drafted with the help of AI tools, then fact-checked against the primary sources listed below before publishing. Daniel is not a licensed financial advisor; this guide is for general education.
Updated October 28, 2026: We clarified that free scores and lender scores usually, but not always, move in the same direction. Reviewed by Daniel Brienza before publishing.
Updated October 27, 2026: we brought the mortgage credit score section up to date (VantageScore 4.0 for all Fannie Mae and Freddie Mac lenders since September 2026, and FHA’s January 2027 start date), added an example of how FHA picks the score that counts, explained what happened to the federal medical debt rule and state medical debt laws, and added a section on buy now, pay later. Reviewed by Daniel Brienza before publishing.
Updated October 23, 2026. We clarified that FICO’s category weights are general guides that vary by person, explained that no plan can guarantee a score increase in 30 days, emphasized that you never need to pay interest to build credit, and added comments from Experian and LendingTree analysts.
Sources
Government and official sources
- Consumer Financial Protection Bureau, “What is a credit score?” (accessed October 2026)
- Consumer Financial Protection Bureau, “What is a credit report?” (accessed October 2026)
- Consumer Financial Protection Bureau, “How long does information stay on my credit report?” (accessed October 2026)
- Consumer Financial Protection Bureau, “How do I dispute an error on my credit report?” (accessed October 2026)
- Consumer Financial Protection Bureau, “Technical correction and update to the CFPB’s credit invisibles estimate” (June 2025)
- Federal Trade Commission, “Free Credit Reports” (accessed October 2026)
- Federal Trade Commission, “Is a credit freeze or fraud alert right for you?” (February 2022)
- Federal Trade Commission, “In FTC Study, Five Percent of Consumers Had Errors on Their Credit Reports That Could Result in Less Favorable Terms for Loans” (February 11, 2013)
- Board of Governors of the Federal Reserve System, “Economic Well-Being of U.S. Households in 2025: Credit” (May 2026)
- Federal Housing Finance Agency, “Homebuying Advances into New Era of Credit Score Competition” (April 22, 2026)
- Federal Housing Finance Agency, “Credit Scores” (updated October 2, 2026)
- U.S. Department of Housing and Urban Development, “Mortgagee Letter 2026-11: Updated Minimum Decision Credit Score Methodology for the Implementation of Alternative Credit Scores” (October 8, 2026)
- U.S. Department of Housing and Urban Development, “Mortgagee Letter 2010-29” (September 3, 2010)
- Consumer Financial Protection Bureau, “CFPB Finalizes Rule to Remove Medical Bills from Credit Reports” (January 7, 2025; archived page notes the July 11, 2025 vacatur)
- Consumer Financial Protection Bureau, “Fair Credit Reporting Act; Preemption of State Laws”, Federal Register (October 28, 2025)
- Consumer Financial Protection Bureau, “Will a Buy Now, Pay Later (BNPL) loan impact my credit scores?” (accessed October 2026)
Credit scoring companies and credit bureaus
- FICO (myFICO), “What’s in your credit score?” (accessed October 2026)
- FICO (myFICO), “What’s not in my FICO Scores” (accessed October 2026)
- FICO (myFICO), “How to Rate Shop and Minimize the Impact to Your FICO Scores” (accessed October 2026)
- FICO, “FICO Unveils Groundbreaking Credit Scores That Incorporate Buy Now, Pay Later Data” (June 23, 2025)
- Experian, “What Is the Average Credit Score in the US?” (March 30, 2026)
- Experian, “Average Car Loan Interest Rates by Credit Score” (September 10, 2026)
- Experian plc, “Equifax, Experian and TransUnion Remove Medical Collections Debt Under $500 From U.S. Credit Reports” (April 11, 2023)
- Experian, “When Do Late Payments Get Reported?” (October 31, 2024)
- Experian, “Can Paying Off Collections Raise Your Credit Score?” (October 19, 2023)
Industry groups, banks and personal finance media
- National Association of Insurance Commissioners, “Credit-Based Insurance Scores” (accessed October 2026)
- Bank of America Better Money Habits, “5 ways to improve your credit score” (accessed October 2026)
- Chase, “Your FICO score, explained” (accessed October 2026)
- Capital One, “How Long Does It Take to Build Credit?” (August 27, 2026)
- Capital One, “How to Build Credit Without a Credit Card” (May 19, 2026)
- NerdWallet, “How to Calculate Your Credit Utilization Ratio” (updated September 24, 2026)
- Bankrate, “Is closing a credit card bad?” (April 18, 2025)
- Ramsey Solutions, “The Best Way to Improve Your Credit Score” (updated April 17, 2025)
- CNBC Make It. Improve your credit score by monitoring your credit utilization rate. July 20, 2021.
- CNN (via KY3). Here’s why your credit score means more right now. January 21, 2026.
- Ballard Spahr, Consumer Finance Monitor, “Federal judge vacates CFPB medical debt rule” (July 15, 2025)
- PYMNTS, “Affirm to Report All Pay-Over-Time Loans to TransUnion” (April 22, 2025)
This article is for educational purposes only and isn’t financial advice. Consider talking with a qualified professional about your situation.

Roth vs. Traditional IRA in 2026: Taxes, Limits and Examples

Credit Report Errors: How to Find, Dispute and Fix Them

HSA Rules for 2026 and 2027: Limits, Taxes and Smart Uses

Asset Allocation by Age: How to Mix Stocks, Bonds and Cash

Debt Consolidation in 2026: Loans, Transfers and Pitfalls

How to Pay Off Credit Card Debt: Avalanche, Snowball and More

How Much Emergency Savings Do You Need? Find Your Number

How to Make a Budget That Actually Works, Step by Step

How Credit Scores Work: FICO Factors and Ways to Improve

You must be logged in to post a comment Login