Saving Strategies
How to Save for a Down Payment: The Complete Guide
You probably don’t need 20% down. Learn how much to save for a house, where to keep the money and a step-by-step plan to reach your down payment goal.

Picture someone like Jasmine, a 32-year-old dental hygienist who rents a two-bedroom apartment. (She’s a made-up example, but her story is a common one.) Every year her rent goes up a little. Every year she tells herself that next year is the year she’ll buy a home.
Then she looks at a listing for a modest house near her job. The price is around $300,000. She does some quick math, assumes she needs 20% down, and lands on $60,000. Her savings account holds $4,200. She closes the app and doesn’t look again for months.
If that sounds familiar, here’s the good news. Jasmine’s math was off in two ways. She probably doesn’t need 20% down. But she also forgot about closing costs, moving costs and a cash cushion. Once you know the real number, saving for it stops feeling like a fantasy and starts looking like a plan with a date on it.
This guide walks you through that plan, one step at a time. You’ll learn how much you actually need, where to keep the money while it grows, and how to save it faster without wrecking the rest of your finances.
What you’ll learn
- The real minimum down payment for each major type of home loan
- How to figure out your full “cash to close” number, not just the down payment
- The honest trade-offs between putting down 3%, 10% and 20%
- Where to keep your savings so it’s safe and still earns something
- Practical ways to find an extra few hundred dollars a month
- When down payment help, family gifts or retirement money make sense, and when they don’t
- A step-by-step plan you can start this week
Table of contents
- What a down payment is and why it matters
- How much do you really need to put down?
- The real trade-off: mortgage insurance and your monthly payment
- Your full number is bigger than the down payment
- Set your savings goal and timeline
- Where to keep your down payment savings
- Ways to find more money to save
- Down payment help, gifts and family money
- Should you use retirement money?
- Your step-by-step action plan
- Common mistakes to avoid
- Myths vs. facts
- Key takeaways
- Frequently asked questions
What a down payment is and why it matters
A down payment is the part of the home’s price you pay in cash up front. The lender covers the rest with a mortgage, which is a loan secured by the house itself. If a home costs $300,000 and you put down $15,000, you borrow the other $285,000.
Lenders care about your down payment because it’s your “skin in the game.” The more of your own money you put in, the less they have to lend. That lowers their risk, and lower risk usually means better terms for you.
Your down payment affects four big things:
- Your loan size. A bigger down payment means you borrow less, so you pay less interest over time.
- Your monthly payment. Borrowing less shrinks the payment you’ll make every month for years.
- Mortgage insurance. On most loans, putting down less than 20% means paying extra for insurance that protects the lender. More on that soon.
- Your equity. Equity is the share of the home you truly own: its value minus what you still owe. A bigger down payment gives you a head start.
Saving for a down payment is often the hardest part of buying a first home. In a 2025 Bankrate survey, 52% of aspiring homeowners called the down payment and closing costs a “very significant” obstacle. You’re not alone if this feels like a big hill to climb.
And the climb is taking longer than it used to. The National Association of Realtors (NAR) found that the typical first-time buyer was 40 years old in its 2025 report, an all-time high. First-time buyers made up just 21% of all buyers, a record low.
None of that means you can’t do it. It means a clear plan matters more than ever. The rest of this guide is that plan.
How much do you really need to put down?
Here’s the short answer: probably less than you think. The idea that everyone needs 20% down is one of the most stubborn myths in personal finance. As Bankrate puts it, “You likely don’t have to save 20% for a down payment on a home.”
The minimum depends on the type of loan you get. Here are the main options.
Conventional loans: as little as 3%
A conventional loan is a regular mortgage that isn’t backed by a government agency. Most follow rules set by Fannie Mae and Freddie Mac, two companies that buy mortgages from lenders. The Consumer Financial Protection Bureau (CFPB) says these loans can require as little as 3% down.
Fannie Mae offers 3% down options such as its HomeReady loan for income-limited buyers and a 97% loan-to-value option for first-time buyers. Bankrate notes that conventional loans generally need a credit score of at least 620.
FHA loans: as little as 3.5%
FHA loans are insured by the Federal Housing Administration, part of the U.S. Department of Housing and Urban Development (HUD). HUD says your down payment can be as low as 3.5% of the purchase price. According to Bankrate, that 3.5% usually applies with a credit score of 580 or higher. With a score from 500 to 579, the minimum rises to 10%.
FHA loans are popular with first-time buyers because the credit rules are more flexible. The catch is mortgage insurance, which we’ll cover in the next section.
VA loans: often 0% down
If you’re a veteran or service member, a VA loan may be the best deal around. The U.S. Department of Veterans Affairs says VA-backed purchase loans often need no down payment, as long as the price isn’t higher than the home’s appraised value. There’s also no monthly mortgage insurance. You may pay a one-time funding fee instead, which is 2.15% of the loan for first-time VA loan users who put down less than 5%.
USDA loans: often 0% down
The U.S. Department of Agriculture backs loans for homes in eligible rural and some suburban areas. Bankrate notes they generally require no down payment, with a credit score of about 640 or higher. Income limits apply. The CFPB says USDA mortgage insurance works much like FHA’s but is typically cheaper.
Jumbo loans: 10% to 20%
A jumbo loan is a mortgage bigger than the limits Fannie Mae and Freddie Mac will buy. These usually require 10% to 20% down and strong credit. Most first-time buyers won’t need one, but it’s worth knowing if you live in a high-cost area.
| Loan type | Typical minimum down | Mortgage insurance? | Good fit for |
|---|---|---|---|
| Conventional | 3% | Yes, under 20% down (can be removed later) | Buyers with fair-to-good credit |
| FHA | 3.5% (580+ score) | Yes, upfront and monthly | Buyers rebuilding credit |
| VA | Often 0% | No monthly insurance; funding fee may apply | Veterans and service members |
| USDA | Often 0% | Yes, upfront and monthly | Rural and some suburban buyers |
| Jumbo | 10% to 20% | Varies by lender | Pricier homes in high-cost areas |
Sources: CFPB, HUD, VA, Fannie Mae and Bankrate. Rules can vary by lender, so check with a few.
What do real buyers put down?
Most first-time buyers don’t put down 20%. In NAR’s 2025 report, the median down payment was 10% for first-time buyers and 23% for repeat buyers. Repeat buyers usually have an advantage: they can roll profit from selling their last home into the next one.
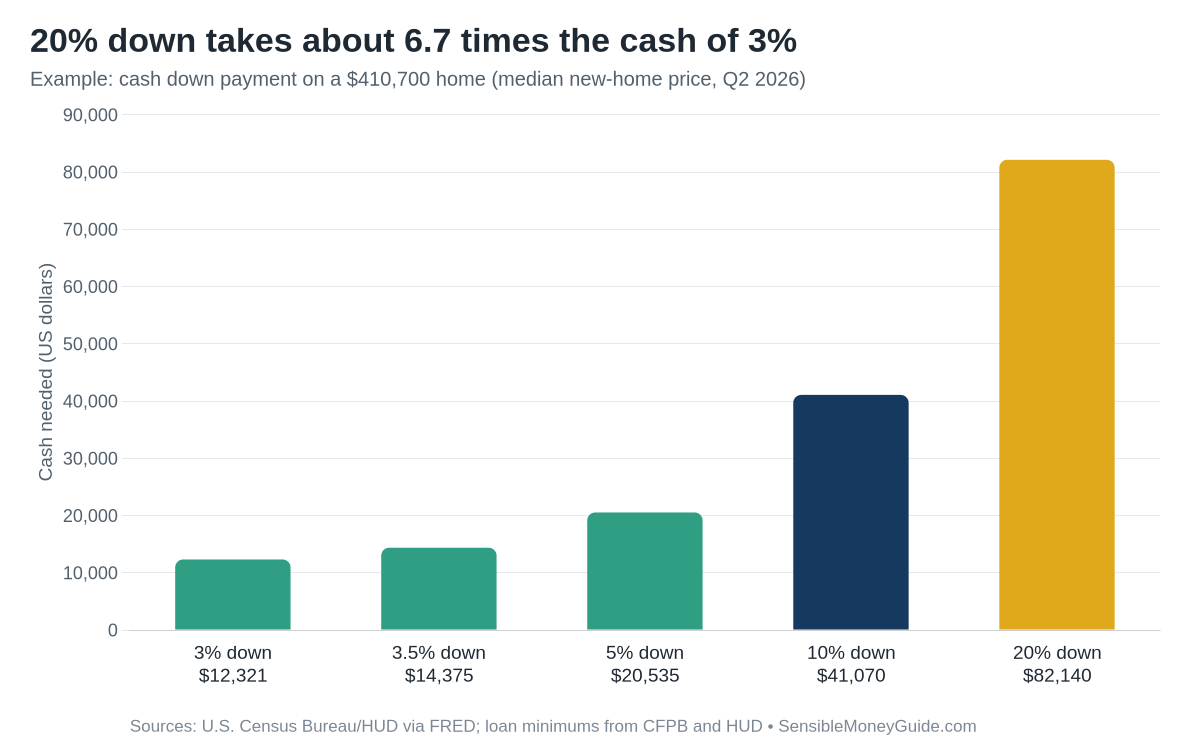
Here’s what different down payments look like on a home priced at $410,700. That’s the median price of a newly built home sold in the second quarter of 2026, according to Census Bureau and HUD data.
So what should you aim for?
This is where experts don’t fully agree, and it’s worth hearing both sides.
Ramsey Solutions, the company behind radio host Dave Ramsey, recommends putting down 20% or more so you can skip private mortgage insurance. For first-time buyers, Ramsey says at least 5% is okay if you’re ready to pay that insurance. Ramsey also pushes a 15-year fixed-rate loan and a payment no higher than 25% of your take-home pay. That’s a conservative approach. It keeps your monthly costs low and your debt short.
Other experts focus on time. NerdWallet, Bankrate and the CFPB all point out that 20% isn’t required. Waiting years to reach 20% can mean paying more rent while prices keep moving. On the other hand, the CFPB warns that “Low-down payment options can mean higher costs over the life of the loan.”
So the honest answer is that it depends. How fast are prices rising where you live? How long would it take you to reach 20%? How stable is your income, and how much would a higher payment squeeze you? A smaller down payment can make sense. Just make sure the monthly payment it creates still fits your budget comfortably.
The real trade-off: mortgage insurance and your monthly payment
If you put down less than 20% on a conventional loan, you’ll almost always pay private mortgage insurance, or PMI. PMI protects the lender, not you, if you stop making payments. You pay for it, usually as part of your monthly mortgage bill.
How much does it cost? Freddie Mac says to expect roughly $30 to $70 a month for every $100,000 you borrow. The CFPB notes that PMI rates vary by your down payment and credit score.
FHA loans have their own version called a mortgage insurance premium. The CFPB explains that it’s required on all FHA loans, with one part paid at closing and another part paid monthly. VA loans skip monthly mortgage insurance but may charge the funding fee mentioned earlier.
Example: 3% vs. 10% vs. 20% down
Let’s run the numbers on that $410,700 home. We’ll use a 30-year fixed rate of 7.40%, which was the national average in Freddie Mac’s weekly survey for the week of October 15, 2026. The figures below cover principal and interest only. Property taxes and homeowners insurance would come on top.
| Down payment | Cash down | Loan amount | Monthly principal and interest | Estimated PMI per month |
|---|---|---|---|---|
| 3% | $12,321 | $398,379 | $2,758 | $120 to $279 |
| 10% | $41,070 | $369,630 | $2,559 | $111 to $259 |
| 20% | $82,140 | $328,560 | $2,275 | $0 |
Here’s what jumps out. Going from 3% down to 20% down takes almost $70,000 more in cash. In return, your monthly payment drops by about $483 in principal and interest, plus you skip PMI. That’s real money every month. But saving that extra $70,000 could take years.
The middle path is often the sweet spot. At 10% down, PMI is cheaper than at 3%, and your loan is smaller. You can also get rid of PMI later.
PMI doesn’t last forever on a conventional loan
This part surprises a lot of people. Federal law gives you at least two ways out of PMI on most conventional loans. According to the CFPB:
- You can ask your loan servicer in writing to cancel PMI once your balance is scheduled to reach 80% of the home’s original value. You can also ask sooner if extra payments get you there early. You’ll need a good payment history and may need to show the home hasn’t lost value.
- Your servicer generally must drop PMI automatically when your balance is scheduled to hit 78% of the original value, as long as you’re current on payments.
FHA and VA loans follow different rules, so ask your lender how long their insurance lasts before you choose.
Pro tip: If you put down less than 20% on a conventional loan, set a calendar reminder for when your balance should reach 80% of the original value. Asking to cancel PMI on time can save you thousands of dollars over the life of the loan.
Your full number is bigger than the down payment
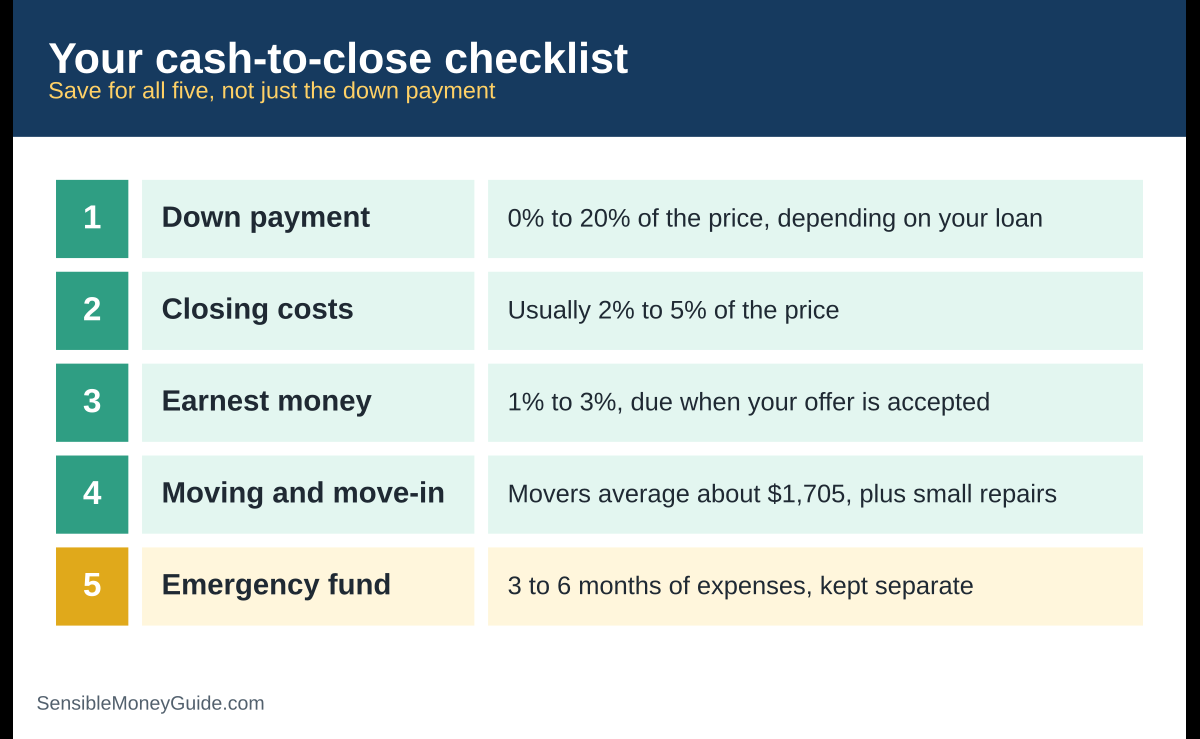
This is the mistake Jasmine made in our opening example, and it trips up a lot of first-time buyers. The down payment is the biggest check you’ll write, but it isn’t the only one. Think in terms of cash to close: all the money you need on hand to finish the purchase and move in without draining your safety net.
Closing costs
Closing costs are the fees to finalize your loan and the sale. They include things like the appraisal, title insurance, lender fees and prepaid taxes. The CFPB says they typically run 2% to 5% of the purchase price, on top of your down payment. On a $300,000 home, that’s $6,000 to $15,000.
You’ll see an estimate early. Your lender sends a Loan Estimate within three days of your application, and you get a Closing Disclosure at least three business days before closing, as Bank of America’s Better Money Habits explains.
Earnest money
Earnest money is a good-faith deposit you pay when a seller accepts your offer. It shows you’re serious. Better Money Habits says it typically runs 1% to 3% of the sale price. The good news is that in a typical purchase it’s applied toward your down payment or closing costs at the end. The catch is timing: you need that cash ready weeks before closing, not on the day.
Moving and move-in costs
Movers aren’t free. Bankrate cites HomeAdvisor data putting the average cost of movers at $1,705. Then come the little things: a new lock, curtains, a lawn mower, a few repairs the inspection turned up. Fannie Mae suggests saving for closing costs, repairs and moving on top of your down payment.
Your emergency fund stays separate
Your emergency fund is not part of your down payment. The CFPB suggests keeping a cushion of three to six months of expenses after you buy. Homes come with surprise bills, like a dead water heater in month two. If you’ve emptied every account to get the keys, one surprise can land on a credit card. Our emergency fund guide walks through how much to keep.
Example: Jasmine’s real number
Let’s go back to Jasmine and her $300,000 house. Say she plans on a conventional loan with 5% down. Here’s her full cash-to-close goal:
| Item | How it’s figured | Amount |
|---|---|---|
| Down payment | 5% of $300,000 | $15,000 |
| Closing costs | 3% of $300,000 (middle of the 2% to 5% range) | $9,000 |
| Movers | National average | $1,705 |
| Move-in and small repairs | Her own estimate | $2,000 |
| Total cash to close | $27,705 |
That’s a lot less scary than the $60,000 she first imagined. It’s also more honest than “just the down payment,” because it includes the costs that catch people off guard. Her emergency fund sits on top of this, in its own account.
Set your savings goal and timeline
A goal without a date is just a wish. So before you save a dollar, you want two numbers: how much, and by when.
What comes first: debt, emergency fund or house?
Here’s another spot where respected voices disagree, so it helps to see the options side by side.
Ramsey Solutions takes a strict, step-by-step view. Its house-saving guide says to pay off debt first and build a full emergency fund of three to six months of expenses before you start saving for a home. Ramsey also says it’s okay to pause retirement investing for a short time, about two years at most, to speed up a down payment.
Fidelity’s approach is lighter. It suggests first making progress on other goals, such as at least $1,000 in emergency savings, any 401(k) employer match and paying down debt, then sending at least some of what’s left toward a down payment. Bankrate also stresses keeping enough in your workplace retirement plan to get any employer match.
Which is right for you? It depends on your debts and your job. If you’re carrying high-interest credit card debt, paying it down first usually wins, since card interest costs more than savings accounts earn. If your income is steady and your debts are small, saving for a house alongside a growing emergency fund can work. Most planners would agree on one thing: don’t buy a home with zero cushion left.
Step 1: Pick a realistic price range
Your down payment goal comes from your target price, so start there. A few rules of thumb can help, though none is perfect:
- Fidelity suggests a home price of roughly three to five times your yearly household income, adjusted for your debts and mortgage rates.
- Better Money Habits suggests keeping your total monthly debt payments under 43% of your gross monthly income. That includes the new mortgage, car loans, student loans and card minimums.
- Ramsey Solutions is stricter. It says your full housing payment should be no more than 25% of your take-home pay.
These give very different answers, and that’s okay. The 43% figure is closer to the most a lender may approve. The 25% rule is a comfort-first target. Most people land somewhere in between. Try the CFPB’s suggestion of working backward from a monthly payment you’d feel good about, not the biggest loan a bank will offer.
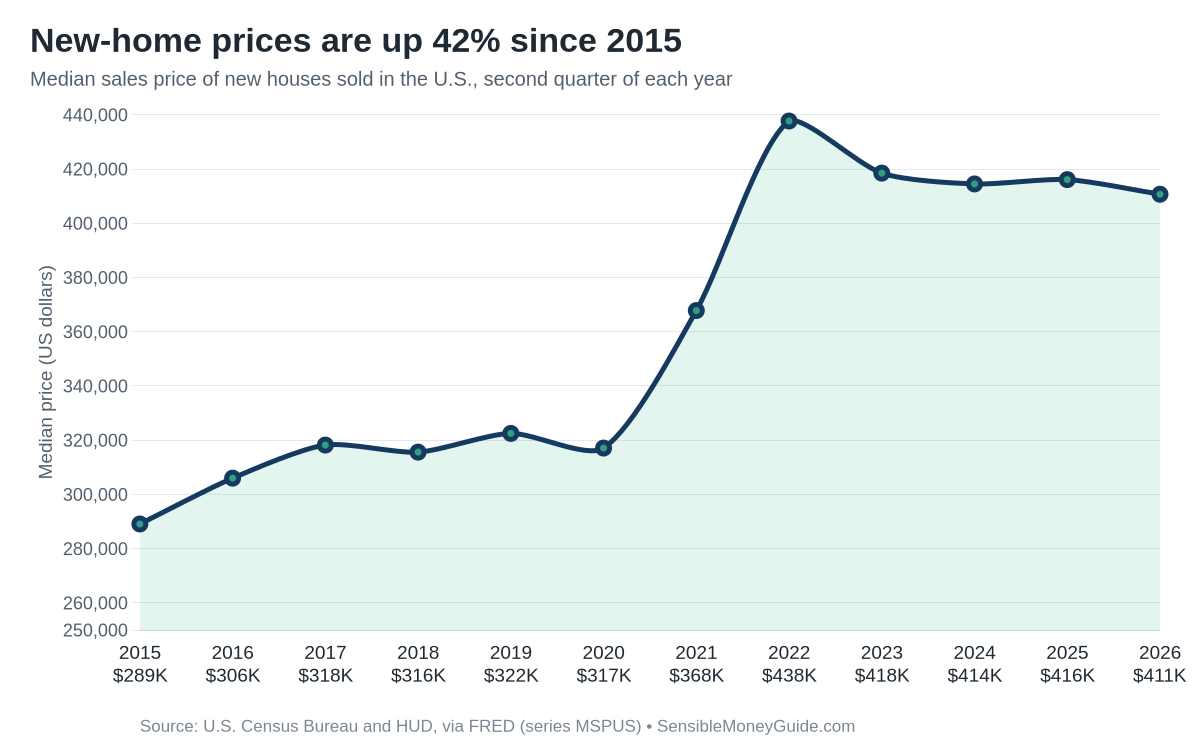
Prices also matter. The chart below shows the median price of newly built homes sold in the U.S. Prices jumped in 2021 and 2022, then leveled off around $410,000 to $420,000.
Step 2: Add up your full cash-to-close goal
Use the method from Jasmine’s example. Take your down payment percentage, add 2% to 5% for closing costs, then add moving and move-in money. Round up a bit. It’s better to have $1,000 extra at closing than $1,000 short.
Step 3: Divide by your timeline
Now subtract what you already have and divide by the number of months until you want to buy. That’s your monthly savings target.
Example: Jasmine’s monthly target
Jasmine needs $27,705 and already has $4,200 saved. Her gap is $23,505.
- To buy in 2 years (24 months): $23,505 ÷ 24 = about $979 a month.
- To buy in 3 years (36 months): $23,505 ÷ 36 = about $653 a month.
Interest on her savings would trim those numbers a little, but it’s smart to plan without counting on it. If $979 a month isn’t doable, she can stretch the timeline, aim for a cheaper home or look for down payment help. All three are fair choices.
For a bigger example, Fidelity runs the math on a $410,000 home with 20% down. That’s $82,000, or about $1,367 a month for five years, starting from zero and earning nothing. Seeing it laid out like that makes it clear why so many first-time buyers choose a smaller down payment.
Watch out: Lenders look at your debts, not just your savings. Paying down a credit card while you save can help you qualify for a better loan. Our guide to how credit scores work explains why.
Where to keep your down payment savings
Down payment money has one job: be there, in full, on the day you need it. That changes where it should live. You want it safe, easy to reach and earning a fair rate. Chasing big returns isn’t the goal.
High-yield savings accounts
A high-yield savings account is a savings account, often at an online bank, that pays much more interest than a typical one. As of early October 2026, Bankrate reported that the best ones were paying around 4% APY. (APY, or annual percentage yield, is the yearly return including compound interest.) Compare that with the FDIC’s national average savings rate of 0.38% in October 2026.
At a bank insured by the FDIC, your deposits are protected up to $250,000 per depositor, per bank, for each account ownership category. Credit union deposits get similar coverage through the NCUA. For most savers, that covers everything.
Money market accounts
A money market account is a bank or credit union account that mixes features of savings and checking. Some let you write checks. Rates are often similar to high-yield savings. They’re insured the same way as other bank deposits.
Certificates of deposit (CDs)
A CD locks in a rate for a set time, such as 6, 12 or 18 months. In exchange, you usually pay a penalty if you pull the money out early. CDs work well if you know your buying date. NerdWallet suggests timing each CD to mature before you expect to need the money.
Build a simple CD ladder
A CD ladder spreads your money across several CDs that come due at different times. It lets you lock in rates without tying up all your cash at once.
Here’s how it might look. Say you have $12,000 saved and plan to buy in about 18 months. You could put $4,000 in a 6-month CD, $4,000 in a 12-month CD and $4,000 in an 18-month CD. Every six months, one CD comes due. If your plans speed up, you’ll have cash coming free soon. If they slow down, you can roll it into a new CD. Keep new monthly savings in your high-yield account so you always have some money you can reach right away.
Money market funds and other cash-like options
Fidelity lists money market funds among the conservative choices for goals within about three years. These are investment funds, not bank deposits. The FDIC notes that non-deposit investment products aren’t covered by deposit insurance, even when a bank sells them. They tend to be low-risk, but they’re a little different from a savings account.
Why not the stock market?
Stocks tend to grow more over long stretches. But over two or three years, they can drop hard and stay down. Imagine saving $30,000, then watching it fall to $22,000 the month you find the right house. NerdWallet says stocks are generally too risky for a short-term goal unless you have 10 or more years. Fidelity takes a similar view: for money needed within about three years, stick with conservative options. If your timeline is longer, Fidelity says some of the money could be invested, depending on how much risk you can stomach.
| Option | Safety | Access | Best for |
|---|---|---|---|
| High-yield savings | FDIC or NCUA insured | Anytime | Most down payment savers |
| Money market account | FDIC or NCUA insured | Anytime, sometimes by check | People who want check access |
| CD | FDIC or NCUA insured | Locked until maturity | A known buying date |
| Money market fund | Not FDIC insured, but low-risk | Usually within a day or two | Brokerage customers |
| Stocks and stock funds | Can lose value | Anytime, but price varies | Timelines of many years |
Example: does the interest rate really matter?
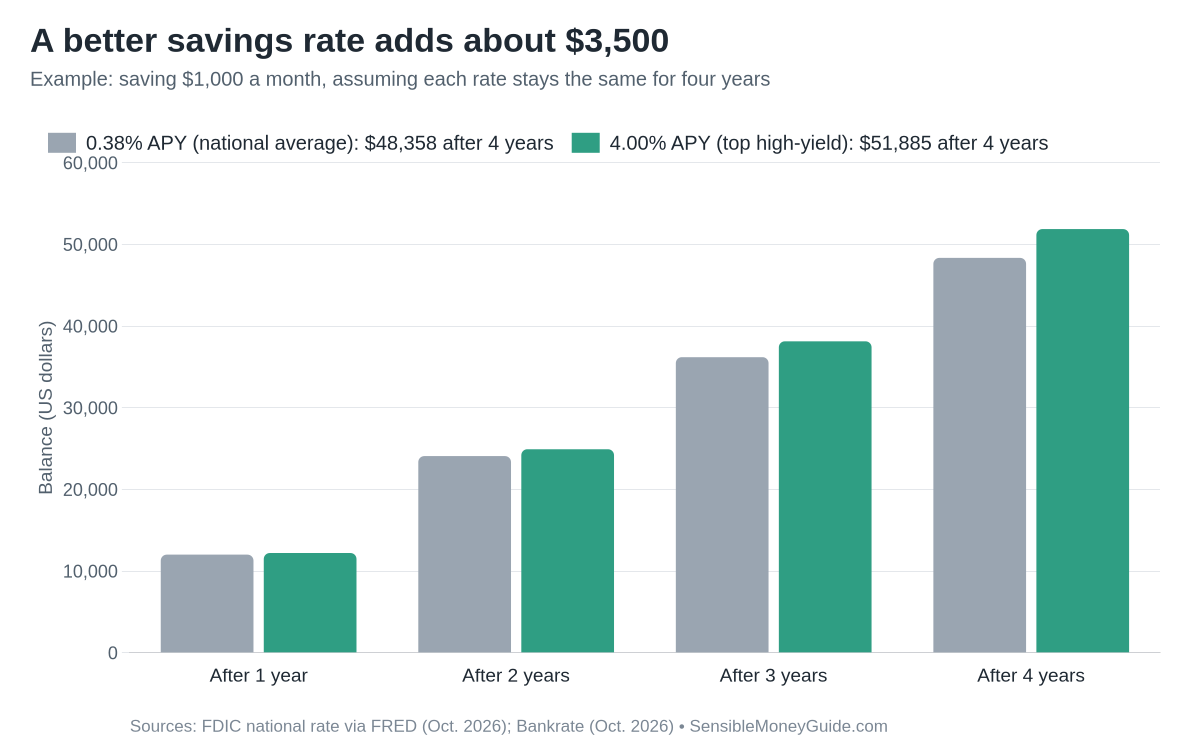
Let’s say you save $1,000 a month for four years. Here’s what you’d have, assuming the rate stays the same the whole time (it won’t, but this shows the gap):
- At 0.38% APY, the national average: about $48,358.
- At 4.00% APY, a top high-yield account: about $51,885.
That’s roughly $3,500 more for the same effort, just from choosing a better account. It’s helpful, but notice what does most of the work: the $48,000 you put in yourself. A good rate is a nice tailwind. Your monthly habit is the engine.
Pro tip: Open a separate account just for your house fund and give it a nickname like “Front Door.” Money you can’t see in your checking account is much easier to leave alone.
Ways to find more money to save
Knowing your number is half the battle. The other half is finding the money each month. Here are the methods that tend to work best, starting with the easiest.
Automate it first
Set up an automatic transfer to your house fund for the day after payday. If your employer allows it, Bankrate suggests splitting your direct deposit so part of each paycheck goes straight into savings. You can’t spend what never lands in checking.
Start with an amount you won’t miss, even $100. Then raise it by $25 or $50 every couple of months. Small, steady bumps feel much easier than one big cut.
Trim your biggest bills
Small cuts add up, but big bills move the needle faster. NerdWallet suggests shopping your car insurance, bundling services, canceling subscriptions you don’t use and tracking every dollar for a month. If you don’t have a spending plan yet, our guide on how to make a budget that actually works is a good place to start.
Here’s a quick example. Say you shave $60 a month off car insurance, $45 off your phone plan and $40 in unused subscriptions. That’s $145 a month, or $3,480 over two years. Nobody would call that a sacrifice, yet it covers nearly 40% of the closing costs on a $300,000 home at 3%.
Send windfalls straight to the fund
A tax refund, a raise, a bonus or a birthday check can jump-start your savings. NerdWallet recommends directing these straight to your house fund. One rule of thumb we like: when you get a raise, send at least half of the increase to savings before you get used to it.
Saving as a couple
If you’re buying with a partner, sit down together and agree on three things: the price range, the date and how much each of you puts in each month. Some couples split it 50/50. Others split it by income, so a partner who earns 60% of the household pay puts in 60% of the savings. Either can work. What matters is that you both agree and can see the progress. A shared savings account with a clear name helps keep you on the same page.
Make your renting years count
Rent isn’t “wasted” money. It buys you a place to live and flexibility while you save. But you can make those years work harder. When your lease comes up, ask whether a cheaper unit, a roommate or a shorter commute could free up cash. Moving to a place that’s $200 a month cheaper adds $4,800 to your house fund over two years. Also, practice your future budget now. If your expected mortgage payment, taxes and insurance would be $500 more than your rent, save that $500 every month. You’ll grow your fund and prove to yourself that the new payment fits.
Earn a little extra
Extra income has no ceiling, while cutting costs eventually does. Freelance work, weekend shifts, delivery gigs or selling things you no longer use can all add up. Be careful with any “opportunity” that asks you to pay money up front. That’s a classic sign of a scam.
Pay down high-interest debt
This one sounds backward, but it often helps. Bankrate notes that “A lower debt load will make you a better candidate for a mortgage.” Lower debt payments can help you qualify for a bigger loan or a better rate. If credit cards are part of your picture, our guide on how to pay off credit card debt can help you plan both goals at once.
Pause other goals, but keep the match
Some people temporarily send less to extra savings goals while they build a house fund. That can make sense. But Bankrate’s advice is to keep contributing enough to get any employer retirement match. A match is free money, and skipping it is a costly way to save.
For more ideas on building a down payment when prices and rates are high, this Yahoo Finance segment is a helpful watch:
Down payment help, gifts and family money
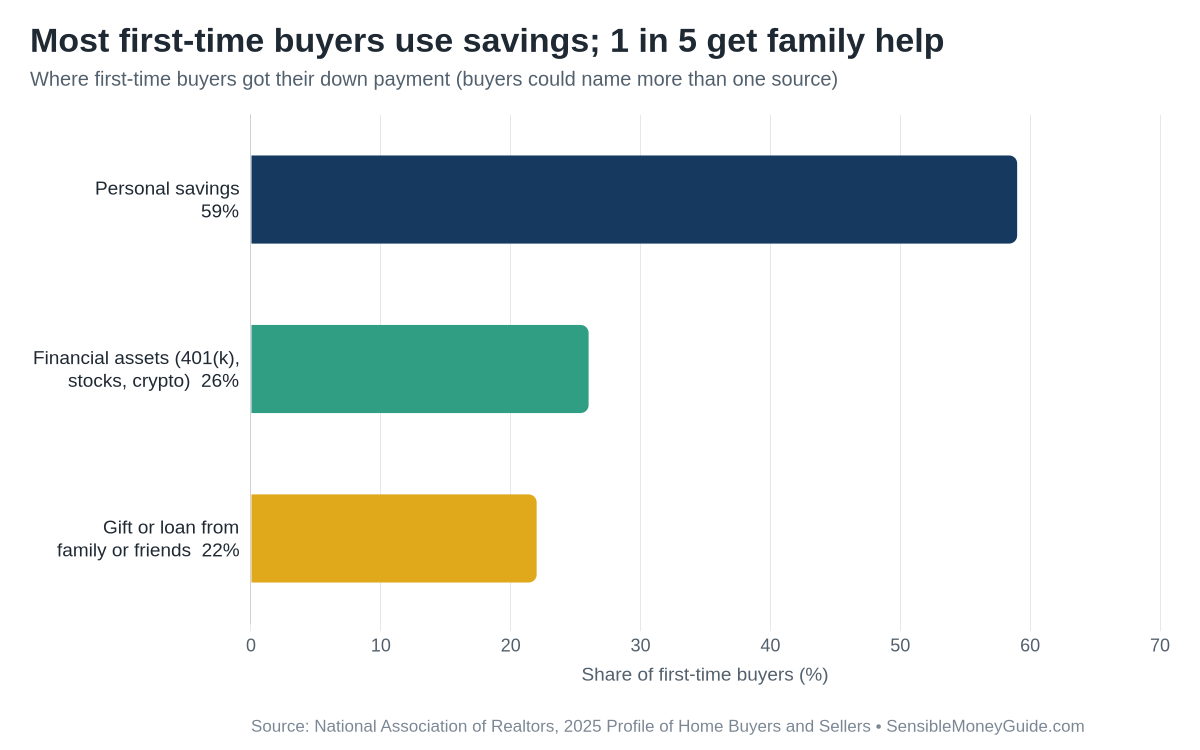
Most first-time buyers don’t do it on savings alone. NAR’s 2025 report found that 59% of first-time buyers used savings for their down payment. But 26% also tapped financial assets like a 401(k), stocks or crypto, and 22% got a gift or loan from family or friends. Buyers could pick more than one source, so the numbers add up to more than 100%.
Down payment assistance programs
Down payment assistance is money from a state, city, county or nonprofit program to help buyers with a down payment or closing costs. It may come as a grant you never repay, a low-interest loan or a “forgivable” loan that disappears if you stay in the home for a set number of years.
Many people never check whether they qualify. Don’t skip this step. The CFPB suggests looking at state and local government programs, plus nonprofits. HUD says you can talk with a HUD-approved housing counselor by calling (800) 569-4287. Counselors can explain local programs, often for free or at low cost.
Programs differ a lot. Some have income or price limits. Some require a homebuyer education class. Some only work with certain lenders. Ask each program what you’d owe if you sell or refinance early.
Gifts from family
If a parent or relative wants to help, that’s a real gift, and many loan programs allow it. There are rules, though. Fannie Mae notes that gifts may need paperwork, and the share of gifted money allowed varies by loan. Bankrate suggests a gift letter, which is a signed note saying the money is a gift and not a loan you’ll have to repay.
Two practical tips. First, tell your lender about any gift early. Second, keep a paper trail. A large, unexplained deposit in your account can slow down your loan approval while the lender asks where it came from.
Loans from family
A loan from family is different from a gift. Lenders usually count it as debt, which can affect how much you qualify for. It can also strain relationships if life gets in the way of repaying. If you go this route, put the terms in writing and be honest with your lender about it.
Should you use retirement money?
It’s tempting. A retirement account might hold more money than anything else you own. And in some cases, the rules allow it. But it usually costs more than people expect, so go in with clear eyes.
IRAs: the $10,000 first-time buyer exception
Normally, taking money out of an IRA before age 59½ triggers a 10% additional tax on top of regular income tax. The IRS lists an exception for qualified first-time homebuyers, up to $10,000. That exception applies to IRAs. It does not apply to 401(k) plans.
Even with the exception, money you pull from a traditional IRA is generally still taxed as income, as NerdWallet points out. Roth IRAs have their own rules. If you’re weighing the two account types, our Roth vs. traditional IRA guide explains the differences.
401(k) loans
Many 401(k) plans let you borrow from yourself. The IRS says you can generally borrow the lesser of half your vested balance or $50,000. Loans usually must be repaid within five years, but the law allows a longer term when you use the loan to buy your main home.
The risk is your job. NerdWallet notes that if you leave your job, the balance generally comes due by your next tax-filing deadline. If you can’t repay it, it’s treated as a withdrawal, with income tax and possibly a 10% penalty if you’re under 59½. You also miss out on market growth on the money while it’s out of your account.
Example: the true cost of a 401(k) withdrawal
Say you’re 35 and pull $10,000 straight out of your 401(k), not as a loan. You’re in the 22% federal tax bracket.
- Federal income tax: 22% of $10,000 = $2,200
- 10% additional tax for early withdrawal: $1,000
- What you keep: $10,000 − $2,200 − $1,000 = $6,800
That’s before any state income tax. You’d give up about a third of the money just to use it today, plus all the growth it could have had by retirement. In most cases, that’s an expensive way to buy a house.
Some experts are fine with a 401(k) loan as a last step for a buyer with a stable job. Others disagree. Ramsey Solutions tells readers not to borrow from or cash out retirement accounts to speed up a down payment. Your safest move is to treat retirement money as off-limits unless you’ve run the numbers with a professional.
Your step-by-step action plan
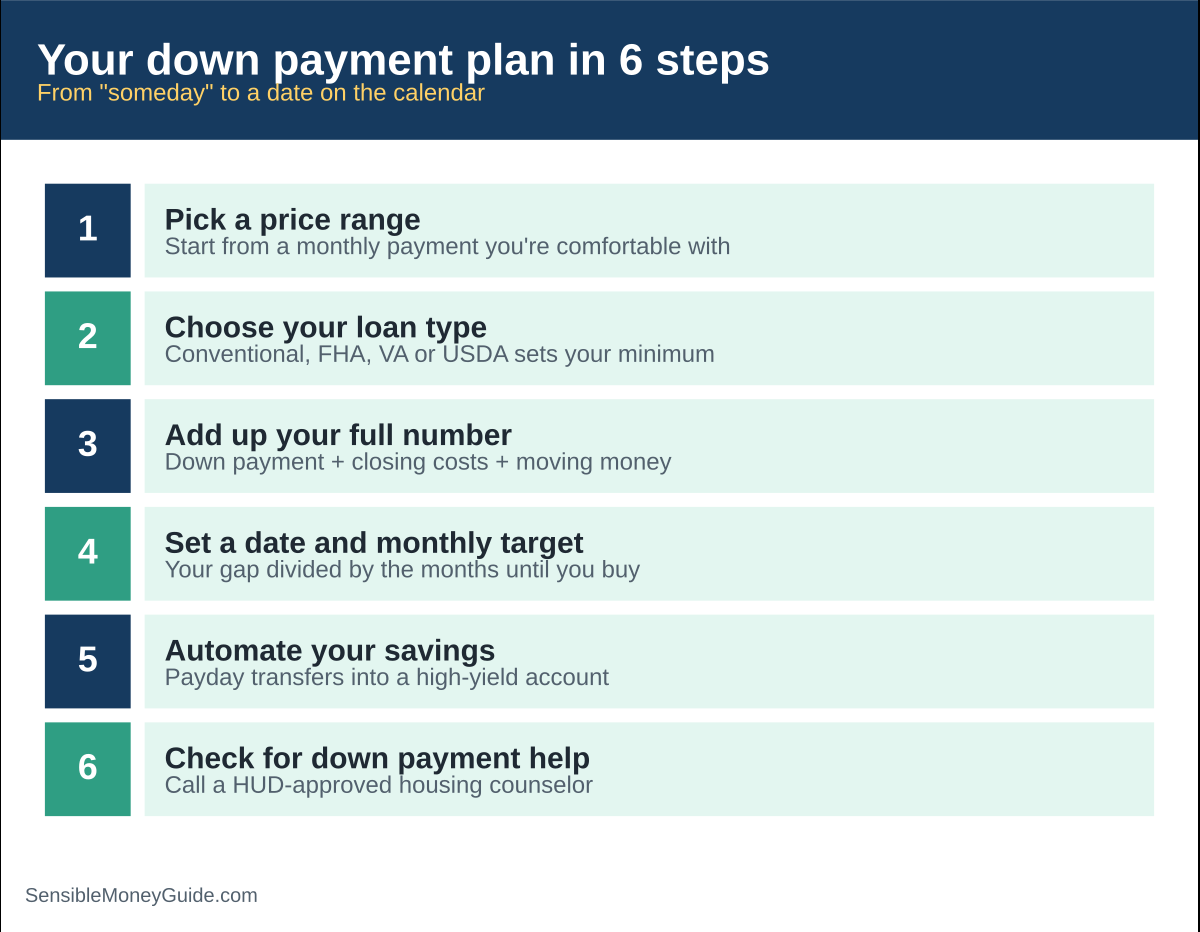
Here’s everything above boiled down into steps you can follow. You don’t need to do them all this week. Just start with the first two.
- Check your starting point. Write down your current savings, monthly take-home pay and debt payments. Pull your free credit reports so you know where you stand.
- Pick a price range. Use a monthly payment you’d feel good about, then work backward. The CFPB’s homebuying tools can help.
- Choose your likely loan type. Conventional, FHA, VA or USDA. This sets your minimum down payment.
- Figure your full cash-to-close number. Down payment plus 2% to 5% for closing costs, plus moving and move-in money.
- Set your date and monthly target. Subtract what you have, then divide by the months until you want to buy.
- Open a separate high-yield savings account. Name it after your goal and set up an automatic transfer for payday.
- Find the money. Trim your biggest bills, send windfalls to the fund and pay down high-interest debt.
- Check for down payment help. Call a HUD-approved housing counselor and look up programs in your state and city.
- Keep your emergency fund whole. Your house fund and your safety net are two different accounts.
- Review every three months. Adjust your target if prices, rates or your income change.
When you reach your goal, the work isn’t over, but it gets more exciting. You’ll get preapproved, start touring homes and, before long, start packing.
Common mistakes to avoid
Even careful savers slip up. These are the mistakes that show up again and again.
- Saving only for the down payment. Closing costs alone can add 2% to 5% of the price. Plan for your full cash-to-close number.
- Emptying the emergency fund to buy. A new home will find ways to cost you money. Keep three to six months of expenses set aside.
- Putting short-term savings in stocks. A market drop right before closing can push your purchase back by a year or more.
- Leaving the money in a 0.01% account. NerdWallet and Bankrate both note that some traditional savings accounts pay about 0.01%. Moving to a high-yield account usually takes less than an hour.
- Making big credit moves before closing. A new car loan or a new credit card can change the numbers your lender approved. Wait until after you have the keys.
- Skipping assistance programs. Many buyers assume they won’t qualify and never check. A phone call to a housing counselor costs nothing.
- Not documenting gifts. Undocumented cash deposits can slow or stall your loan. Get a gift letter and keep records.
- Buying at the top of your approval. A lender’s maximum isn’t the same as a comfortable payment. Leave room for life.
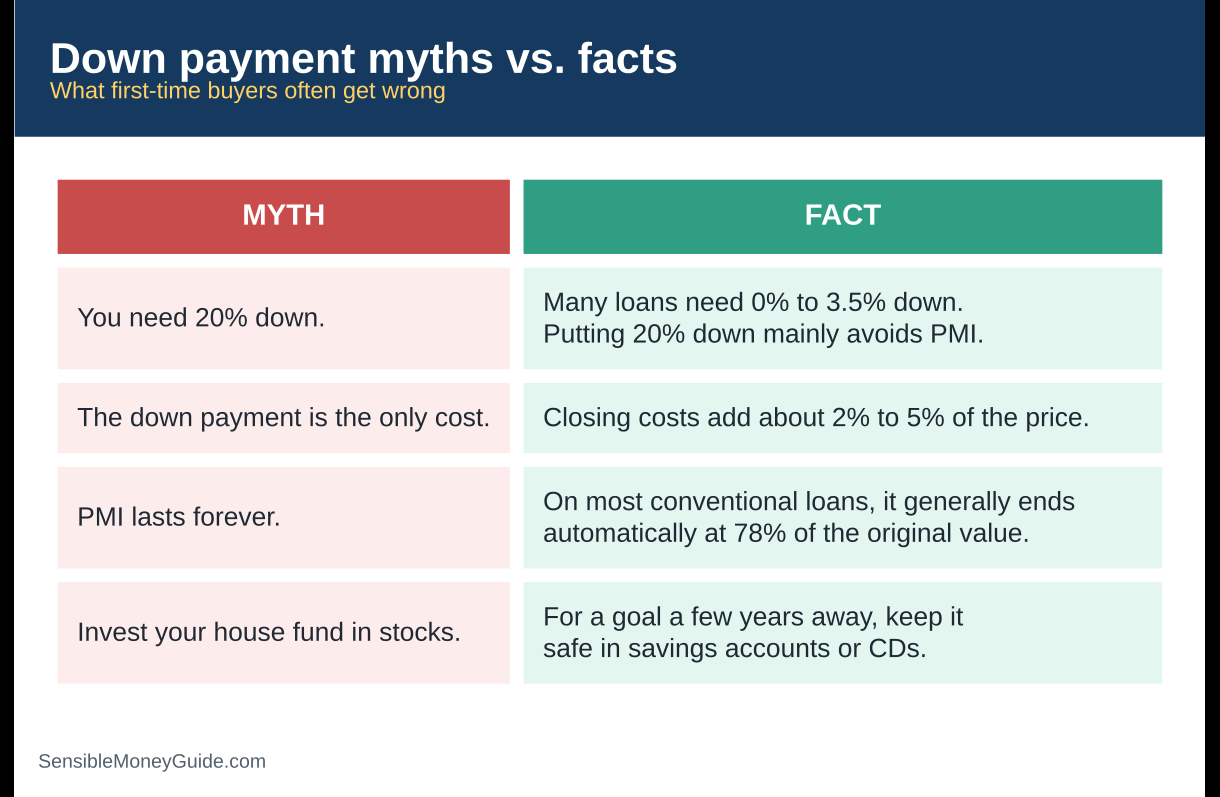
Myths vs. facts
Myth: You need 20% down to buy a home.
Fact: Conventional loans can require as little as 3%, FHA loans 3.5% and VA and USDA loans often 0%. Twenty percent mainly helps you avoid PMI.
Myth: The down payment is the only cash you need.
Fact: Closing costs typically add 2% to 5% of the price, plus earnest money timing, moving costs and repairs.
Myth: PMI lasts for the life of the loan.
Fact: On most conventional loans, you can ask to cancel it at 80% of the original value, and it generally ends automatically at 78%. FHA rules are different.
Myth: You need perfect credit.
Fact: FHA loans can work with credit scores as low as 580 at 3.5% down, or 500 to 579 with 10% down, according to Bankrate.
Myth: Your house fund should be invested to grow faster.
Fact: For a goal a few years away, safety beats growth. Fidelity and NerdWallet both point to savings accounts, CDs and other conservative options.
Myth: Using family money is cheating.
Fact: About 22% of first-time buyers got help from family or friends, per NAR. It’s common and allowed, as long as it’s properly documented.
Key takeaways
- You likely don’t need 20% down. The typical first-time buyer put down 10% in NAR’s 2025 report.
- Minimums range from 0% (VA and USDA) to 3% (conventional) and 3.5% (FHA).
- Putting down less than 20% usually means mortgage insurance, but on conventional loans it can be removed later.
- Plan for your full cash-to-close number: down payment, 2% to 5% closing costs, moving and repairs.
- Keep your emergency fund separate. Don’t empty it to buy a house.
- Keep down payment savings in a high-yield savings account, money market account or CDs, not stocks.
- Your monthly savings habit matters more than your interest rate, but a good rate still helps.
- Check down payment assistance before you decide you can’t afford to buy.
Frequently asked questions
How much should I save for a house?
Start with your loan’s minimum down payment, then add 2% to 5% of the price for closing costs, plus moving and move-in money. On a $300,000 home with 5% down, that’s roughly $27,700. Keep your emergency fund on top of that.
How long does it take to save for a down payment?
It depends on your goal and how much you can save each month. Saving $1,000 a month gets you about $24,000 in two years, before interest. Divide your total goal by your monthly savings to find your own timeline.
Can I buy a house with no money down?
Possibly. VA loans for eligible veterans and service members and USDA loans in eligible areas often need no down payment. You’ll still usually need cash for closing costs, though some programs and sellers can help cover them.
Is 10% down enough?
For many buyers, yes. It’s the median for first-time buyers in NAR’s 2025 report. You’ll likely pay PMI on a conventional loan, but you can usually cancel it once you reach enough equity.
Can I use my 401(k) for a down payment?
You can sometimes borrow from it or withdraw from it, but both have costs. Withdrawals before 59½ usually face income tax and a 10% additional tax. A loan can come due quickly if you leave your job. The $10,000 first-time buyer exception applies to IRAs, not 401(k)s.
Where should I keep my down payment money?
Most people do best with a high-yield savings account at an insured bank or credit union. CDs can work if you know when you’ll buy. Avoid stocks for money you’ll need in the next few years.
Can family give me money for a down payment?
Yes, many loans allow gifts. Your lender will likely want a gift letter stating the money doesn’t need to be repaid. Tell your lender early and keep records of the transfer.
Does earnest money count toward my down payment?
Usually, yes. Earnest money is typically credited toward your down payment or closing costs at closing. You just need the cash available when your offer is accepted, which is weeks before closing day.
Your next step this week
Open a separate high-yield savings account for your house fund, name it after your goal and set up an automatic transfer for the day after your next payday. Pick an amount you won’t miss, even $100. You can raise it later. What matters is that your house fund starts growing this week, not “someday.”
Sources
- Consumer Financial Protection Bureau, Determine your down payment, accessed October 2026.
- Consumer Financial Protection Bureau, What is mortgage insurance and how does it work?, accessed October 2026.
- Consumer Financial Protection Bureau, When can I remove private mortgage insurance (PMI) from my loan?, accessed October 2026.
- U.S. Department of Housing and Urban Development, Loans, accessed October 2026.
- U.S. Department of Veterans Affairs, Purchase loan, accessed October 2026.
- U.S. Department of Veterans Affairs, VA funding fee and loan closing costs, accessed October 2026.
- Internal Revenue Service, Retirement topics: Exceptions to tax on early distributions, updated December 11, 2025.
- Internal Revenue Service, Retirement topics: Loans, accessed October 2026.
- Federal Deposit Insurance Corporation, Understanding deposit insurance, accessed October 2026.
- Federal Reserve Bank of St. Louis (FRED), data from the U.S. Census Bureau and HUD, Median Sales Price of Houses Sold for the United States (MSPUS), accessed October 2026.
- Federal Reserve Bank of St. Louis (FRED), data from the FDIC, National Rate: Savings (SNDR), October 2026 data.
- Federal Reserve Bank of St. Louis (FRED), data from Freddie Mac, 30-Year Fixed Rate Mortgage Average in the United States (MORTGAGE30US), week of October 15, 2026.
- National Association of Realtors, First-time home buyer share falls to historic low of 21%, median age rises to 40, November 4, 2025.
- Fannie Mae, What you need to know about down payments, accessed October 2026.
- Freddie Mac, Breaking down PMI, accessed October 2026.
- Fidelity Investments, How to save for a house or down payment, January 13, 2026.
- Bank of America Better Money Habits, The home buying process: What to expect when buying a home, accessed October 2026.
- Bankrate, How to save for a down payment (Allison Martin), February 9, 2026.
- Bankrate, What is the average interest rate for savings accounts?, October 2026.
- NerdWallet, How to save for a house: A step-by-step guide (Kate Wood), updated March 9, 2026.
- Ramsey Solutions, How much down payment do you need on a house?, updated September 16, 2026.
- Ramsey Solutions, How to save for a house, updated September 17, 2026.
This article is for educational purposes only and isn’t financial advice. Consider talking with a qualified professional about your situation.

Saving Strategies
Emergency Fund Guide: How Much You Need and Where to Keep It
How much should you keep in an emergency fund, and where? Learn how to find your number, where to keep it safe, and how to build it on any budget.
Picture someone like Maria, a 34-year-old nurse. (She’s a made-up example, but you probably know someone just like her.) It’s a Tuesday night in February. She’s driving home from a long shift when the “check engine” light comes on. The next morning, the mechanic calls with the news: $1,400 for a new alternator and a belt.
Maria has two choices. She can put it on a credit card and pay it off slowly, with interest. Or she can move money from a savings account she set up two years ago, pay the bill, and go back to work without losing sleep.
That second option is what this guide is about. An emergency fund is boring. It doesn’t grow fast, and nobody brags about it at parties. But it’s the one money tool that makes almost every other money goal easier, from paying off debt to investing for retirement.
By the end of this guide, you’ll know how much you need and where to keep it. You’ll also know how to build it, even if money is tight right now.
What you’ll learn
- What counts as an emergency fund, and what doesn’t
- Why even $500 to $2,000 can change how you feel about money
- How to figure out your own target number, step by step
- The safest places to keep your fund so it earns something
- Simple ways to build it, even on a tight budget
- Whether to save first or pay off debt first
Table of contents
- What an emergency fund is (and isn’t)
- Why it matters more than you think
- How much you need: the starter goal and the full goal
- How to find your own number
- How many months is right for you?
- Where to keep your emergency fund
- How to build it, even on a tight budget
- When to use it (and when not to)
- Emergency fund or debt payoff first?
- Common mistakes to avoid
- Myths vs. facts
- Your step-by-step action plan
- Key takeaways
- Frequently asked questions
What an emergency fund is (and isn’t)
An emergency fund is money you set aside only for surprise costs and income loss. The Consumer Financial Protection Bureau (CFPB) describes it as cash for unplanned expenses like car or home repairs, medical bills, or a drop in income (CFPB).
Think of it as your own private insurance policy. You pay the “premium” a little at a time. When something goes wrong, you file a claim with yourself. No phone calls, no forms, no interest.
Here’s what an emergency fund is not:
- It’s not your checking account. Money that sits next to your grocery and gas spending tends to get spent. Keep it separate.
- It’s not a vacation fund. Planned costs, like a trip, holiday gifts or back-to-school shopping, deserve their own savings buckets.
- It’s not an investment. The job of this money is to be there, at full value, the day you need it. Growth is a nice bonus, not the goal.
- It’s not a credit card. A credit limit can feel like a safety net. But it’s a loan, and the bill comes with interest.
That last point matters a lot. A card can be cut or lowered right when times get hard. Your own cash can’t.
The two jobs your fund does
Most people think of an emergency fund as “car repair money.” That’s one job. But it actually does two different jobs.
Job 1: Absorb small shocks. A broken phone screen. A vet bill. A $600 dental crown. These pop up a few times a year for most households.
Job 2: Replace your income for a while. A layoff, a long illness, or a big cut in hours. These are rarer but much more expensive.
A starter fund handles Job 1. A full fund handles Job 2. We’ll get to the right size for each in a minute.
Why it matters more than you think
Surprise bills aren’t rare. They’re normal. In the Federal Reserve’s latest survey of U.S. households, 59% of adults said they’d had at least one major unexpected expense in the past year (Federal Reserve). The most common were car repairs or replacement (30%), home or appliance repairs (22%) and big medical bills (21%).
So the question isn’t whether you’ll face one. It’s whether you’ll have the cash when you do.
Many households are one bill away from debt
Each year, the Fed asks people how they’d pay for a surprise $400 expense. In the most recent survey, done in October 2025, 63% said they’d use cash or its equivalent. That means money in savings, or a credit card they’d pay off in full at the next statement (Federal Reserve).
That number climbed steadily for years, hit a high of 68% in 2021, and then slipped back. It’s been stuck at 63% for four years in a row (Federal Reserve SHED data).
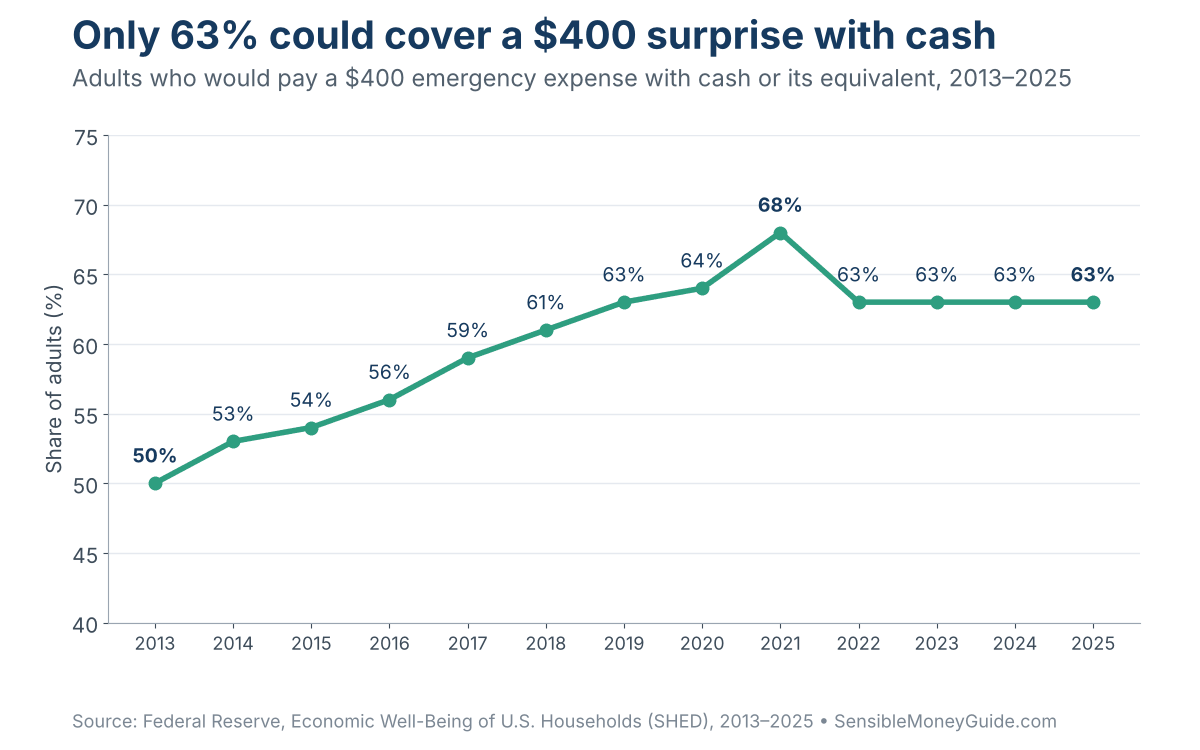
The other 37% would have to borrow, sell something, or skip the bill. Respondents could pick more than one answer: 15% said they’d put it on a credit card and pay it off over time, 10% would borrow from a friend or family member, and 12% couldn’t pay it right now at all (Federal Reserve).
A broader measure tells a similar story. Just 55% of adults said they had enough savings to cover three months of expenses if they lost their main source of income (Federal Reserve). Younger adults have it hardest. Only 37% of people ages 18 to 29 had that cushion in 2025, compared with 71% of people 60 and older (Federal Reserve SHED data).
Private surveys tell a similar story. Bankrate’s 2026 Annual Emergency Savings Report, based on surveys done in 2025, found that 46% of U.S. adults have enough saved to cover three months of expenses, and 27% could cover six months or more (Bankrate). Six in 10 said they felt uncomfortable with how much they had saved.
It’s not just about money. It’s about stress.
Here’s the part that surprised a lot of people, including financial pros. In 2025, Vanguard published a study of more than 12,000 of its investors. The researchers looked at what predicted how good people felt about their finances (Vanguard).
Having at least $2,000 in emergency savings was linked to a 21% higher financial well-being score than having no emergency savings. Having three to six months of expenses saved added another 13% on top of that.
The day-to-day differences were striking, too:
- Investors with no emergency savings said they spent about 7.3 hours a week dealing with their finances. Those with at least $2,000 spent about 3.7 hours.
- About half (51%) of people with no emergency savings said their financial stress went up over the past year, versus 15% of those with $2,000 or more.
- People with no emergency savings said money worries distracted them at work for about 6.1 hours a week. For those with $2,000 or more, it was 1.5 hours.
One honest caveat: this study shows a link, not proof of cause. People who have savings may differ in other ways. And Vanguard’s investors aren’t a perfect mirror of all Americans. Still, the pattern makes sense to anyone who’s lain awake worrying about a bill.
Cash beats credit when things go wrong
When there’s no cash, the backup plan is usually a credit card. That gets expensive fast. In the second quarter of 2026, the average interest rate on credit card accounts that were charged interest was 22.15% (Federal Reserve G.19).
We’ll run the real math on that later. For now, just know this: a $1,500 repair can quietly turn into a $1,900 repair if you pay it off slowly on a card.
Want a quick, friendly overview before we dig into the numbers? This short video from Two Cents, a personal finance series from PBS Digital Studios, makes the case for why you need an emergency fund.
How much you need: the starter goal and the full goal
You’ve probably heard “three to six months of expenses.” That’s a good rule. But if you’re starting from zero, a number like $15,000 can feel so far away that you never start. So it helps to break it into steps.
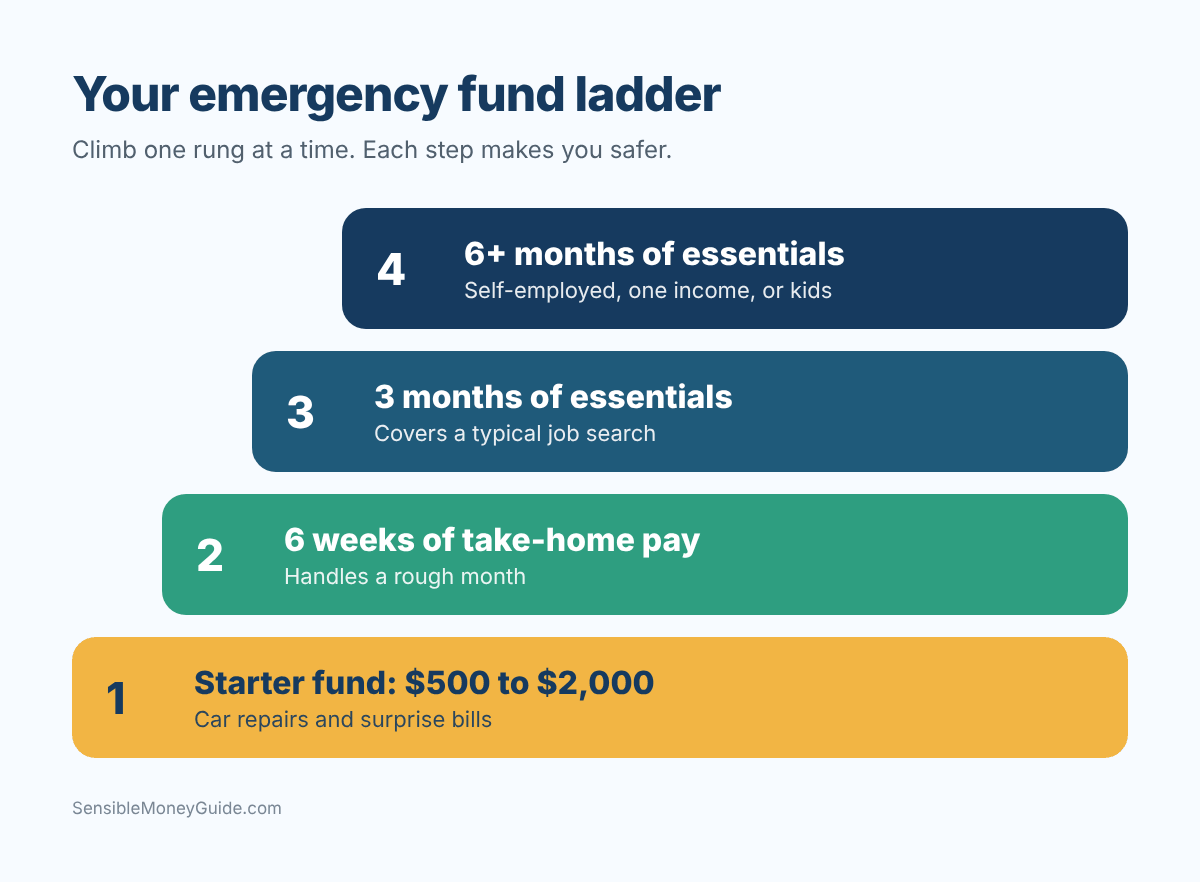
Most experts agree on a two-stage plan: a small starter fund first, then a full fund later. Where they differ is on the exact amounts.
Stage 1: The starter fund
Your starter fund handles the everyday surprises, like a tow, a co-pay or a broken appliance. Here’s what some well-known voices suggest:
- NerdWallet suggests $500 as a first goal if the bigger target feels out of reach. It notes that saving just $10 a week would get you past $500 within a year (NerdWallet).
- Fidelity suggests starting with $1,000 (Fidelity).
- Ramsey Solutions makes a $1,000 starter fund Baby Step 1 in Dave Ramsey’s plan, before paying off debt (Ramsey Solutions).
- Vanguard’s research found that having at least $2,000 saved was linked to a 21% higher financial well-being score, a bigger boost than the extra 13% linked to having three to six months saved (Vanguard).
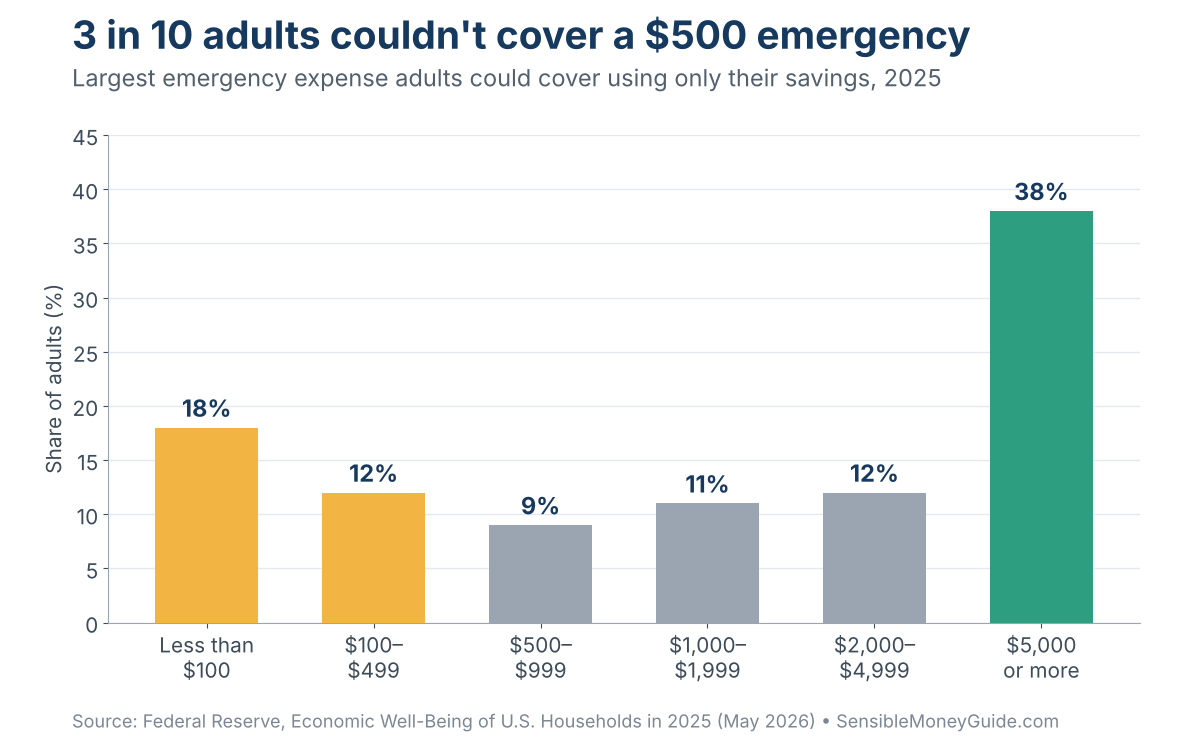
So which is right? Any of them is a great start. If money is very tight, aim for $500. If you can stretch, go for $1,000 to $2,000. The Fed’s data shows why that range matters. In 2025, 18% of adults said the largest emergency they could cover using only savings was under $100, and another 12% said $100 to $499 (Federal Reserve).
Stage 2: The full fund
Your full fund is the one that covers a job loss or a long illness. The common guideline is three to six months of essential expenses. Fidelity, NerdWallet and Ramsey Solutions all use that range (Fidelity; NerdWallet; Ramsey Solutions).
Not everyone agrees, though. Personal finance author Suze Orman has long argued for a much bigger cushion. In a 2017 talk covered by CNBC, she said people should keep eight to 12 months of living expenses saved. One reason: a job search can take far longer than expected (CNBC). In her words, “You need to know that you are going to be secure.”
Who’s right? It depends on your life. Orman’s bigger target gives more peace of mind, but it can take years to reach. For many households, money beyond six months might do more good paying down high-interest debt or going into a retirement account. On the other hand, if you’re self-employed or your field has frequent layoffs, a bigger number makes a lot of sense. We’ll help you pick in the next two sections.
A third view: weeks, not months
Researchers at the JPMorgan Chase Institute studied the bank accounts of millions of families. They found that a typical family needed about six weeks of take-home pay in cash. That’s enough to get through a month when income drops and spending spikes at the same time (JPMorgan Chase Institute). And 65% of families didn’t have that much.
That’s a helpful middle step. Six weeks of pay is smaller than three months of expenses, and it protects you from the most common money squeezes. Think of it as a checkpoint on the way to your full fund.
How to find your own number
Rules of thumb are fine. Your own number is better. Here’s how to figure it out in about 20 minutes with your last few bank statements.
Step 1: List only your essential expenses
Your emergency fund doesn’t need to cover your whole lifestyle. It needs to cover the bills you’d still have to pay if your income stopped tomorrow. Fidelity’s list of essentials is a good guide: rent or mortgage, utilities, basic groceries, health care, insurance premiums, child care or tuition, transportation, and minimum debt payments (Fidelity).
Leave out the nice-to-haves. Dining out, streaming services, vacations and new clothes can pause in a real emergency.
Step 2: Use real numbers, not guesses
Pull the last three months of bank and card statements. Add up each essential category and divide by three. Real numbers are often higher than what we guess, especially for groceries and gas.
Step 3: Multiply by your months
Multiply your monthly essentials by three to get the low end of your target. Multiply by six for the high end.
Worked example 1: Maria’s number
Let’s go back to Maria, our made-up nurse. Here’s what her essential spending looks like each month:
| Essential expense | Monthly cost |
|---|---|
| Rent | $1,450 |
| Utilities (power, water, gas) | $210 |
| Groceries | $520 |
| Insurance (car and renters) | $260 |
| Car payment and gas | $480 |
| Phone and internet | $120 |
| Minimum debt payments | $150 |
| Health costs (co-pays, prescriptions) | $90 |
| Total essentials | $3,280 |
Here’s the simple math:
- Three months: $3,280 × 3 = $9,840
- Six months: $3,280 × 6 = $19,680
So Maria’s full-fund target is somewhere between about $10,000 and $20,000. Her starter goal could be $1,000 to $2,000. That’s a much friendlier first number than $20,000.
Watch out: If you have a high-deductible health plan, add your deductible to your target, or keep it in a health savings account. A single ER visit can use up a big chunk of a small fund.
How many months is right for you?
Three months or six? Or more? The honest answer is that it depends on how likely you are to lose income and how long it might take to replace it.
How long job searches actually take
The Bureau of Labor Statistics (BLS) tracks how long unemployed people have been looking for work. In September 2026, the median length of unemployment was 11.5 weeks, or a little under three months (BLS). “Median” means half of unemployed people had been out of work for less time, and half for longer.
But look at the full picture. About 27% of unemployed people had been looking for 27 weeks or more. That’s over six months.
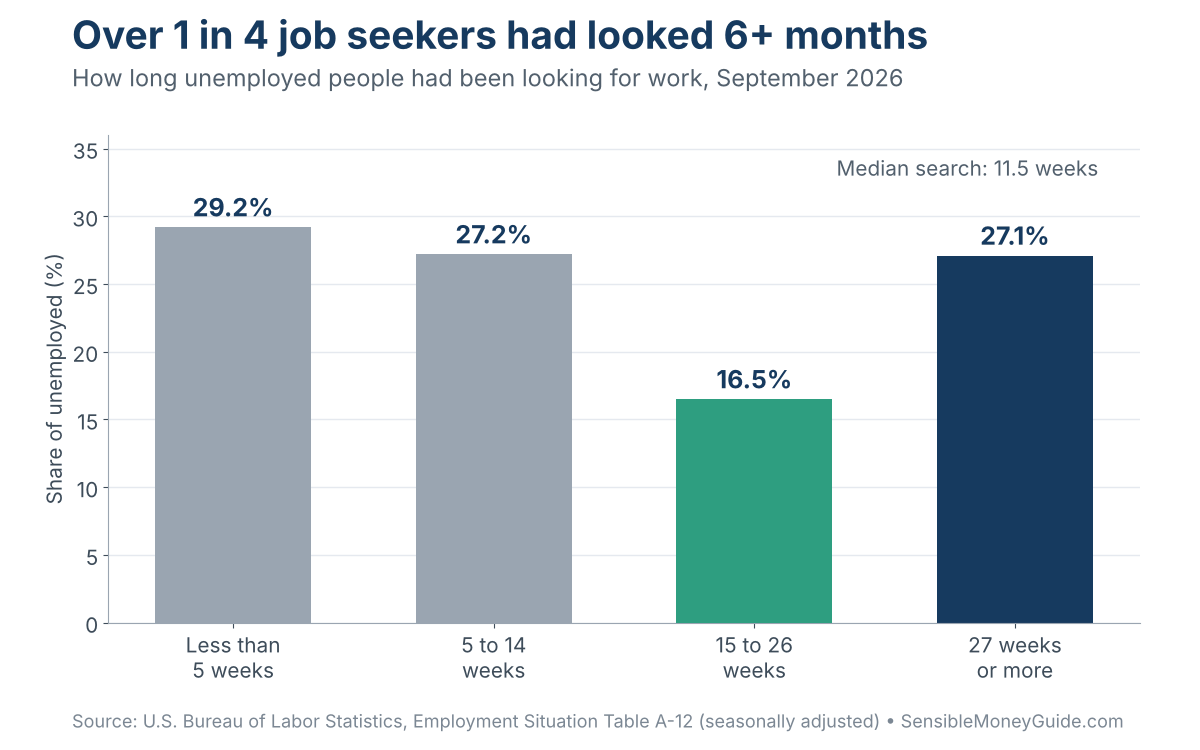
This is why three months is a floor, not a ceiling, for many people. Right now, more than one in four unemployed people have been looking for over six months, so a long search is far from rare. Unemployment benefits can help, but they usually replace only part of your pay, for a limited time.
Lean toward three months if:
- You have a stable job in a field with steady demand, like health care or teaching.
- Your household has two steady incomes, and you could live on one.
- You have no kids or other people who depend on you.
- You rent and drive a newer, reliable car.
Lean toward six months (or more) if:
- You’re self-employed, work on commission, or have income that changes month to month.
- You’re the only earner in your home, or you support kids or aging parents.
- You work in an industry with frequent layoffs.
- You own an older home or drive an older car.
- You have a health condition that could keep you from working.
- You’re retired or living on a fixed income.
Fidelity’s guide lists many of these same reasons for saving more than the basic range (Fidelity).
Special situations
If you’re self-employed or a gig worker. Your income may swing a lot from month to month, and you don’t get unemployment benefits in most cases. Six months or more is a sensible place to start. It also helps to keep your tax money in a separate account, so a quarterly tax bill never eats into your emergency cushion.
If you own a home. Homeowners pay for every repair themselves. A new water heater, a roof patch or a broken air conditioner can cost thousands of dollars. Some homeowners keep a separate home repair fund on top of their emergency fund, so a big repair doesn’t wipe out their job-loss cushion.
If you’re retired. You may not face a layoff, but you do face market drops, health costs and big repairs. Fidelity notes that retirees and people on fixed incomes may want to save more than the usual range (Fidelity). Some retirees choose to keep extra cash on hand so they don’t have to sell investments when prices are down. A financial planner can help you find the right mix.
If you’re young and just starting out. The Fed’s numbers show that adults under 30 are the least likely to have a three-month cushion (Federal Reserve SHED data). That’s normal, since early-career pay is lower. Focus on the starter fund first, then build toward six weeks of take-home pay, then three months. Each step makes you safer than the last.
Pro tip: Two-income couples sometimes think they need less. That’s true only if you could cover essentials on the smaller paycheck alone. Run that test before you settle on three months.
Where to keep your emergency fund
Where you park your fund matters almost as much as how big it is. The right spot checks three boxes:
- Safe. The money won’t lose value or disappear.
- Easy to reach. You can get it within a day or two, without penalties.
- A little out of sight. It’s not so handy that you dip into it for everyday spending.
Earning some interest is a fourth box. It’s nice, but it comes last.
Why FDIC and NCUA insurance matters
Before you pick an account, check that it’s insured. The Federal Deposit Insurance Corporation (FDIC) insures deposits at member banks up to $250,000 per depositor, per bank, for each account ownership category (FDIC). That covers checking, savings, money market deposit accounts and certificates of deposit (CDs). It does not cover stocks, bonds, mutual funds or crypto.
Credit unions have their own version. The National Credit Union Administration (NCUA) insures individual accounts at federally insured credit unions up to $250,000 (NCUA).
For almost everyone, that means an emergency fund in an insured bank or credit union account is as safe as money gets. The CFPB says a bank or credit union account is “generally considered one of the safest places to put your money” (CFPB).
Your main options, compared
| Option | Safety | Access | Earnings | Best for |
|---|---|---|---|---|
| High-yield savings account (online bank) | FDIC or NCUA insured | Usually 1 to 2 business days | Often well above average | Most people’s main fund |
| Regular savings at your local bank | FDIC or NCUA insured | Same day | Low; national average 0.37% | Quick-access starter cash |
| Money market deposit account (bank) | FDIC or NCUA insured | Same day to 2 days | Varies; can be competitive | People who want check-writing |
| Money market fund (brokerage) | Not FDIC insured; low risk | About 1 business day | Tracks short-term rates | Larger funds held at a brokerage |
| Short-term CDs or Treasury bills | Insured (CDs) or U.S. government-backed (T-bills) | Locked until maturity, or a penalty or sale | Fixed for the term | The “back half” of a large fund |
| Cash at home | Not insured | Instant | None | A small amount for power outages |
High-yield savings accounts: the best fit for most people
A high-yield savings account is simply a savings account that pays a higher interest rate than average. Most are offered by online banks, which have lower costs than banks with branches.
The gap can be big. The FDIC’s national average rate for savings accounts was just 0.37% in September 2026 (FDIC national rate, via FRED). Meanwhile, NerdWallet’s October 2026 list of top high-yield accounts showed rates from 3.10% to 5.00% APY, with the top rate being a limited-time promotion with strings attached (NerdWallet).
APY, or annual percentage yield, is the amount your money earns in a year, including interest on your interest. Rates on savings accounts can change at any time, so treat any number as a snapshot.
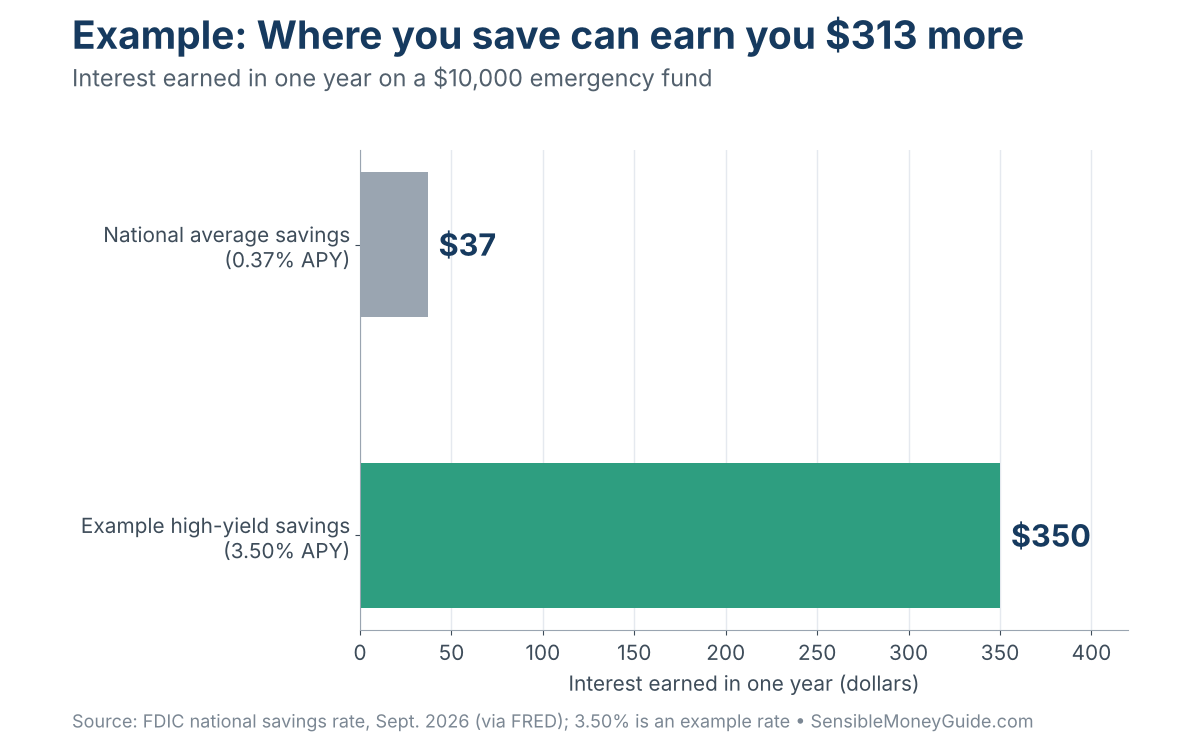
Worked example 2: What $10,000 earns in a year
Let’s say you’ve built a $10,000 emergency fund. Here’s what it could earn in one year at two different rates, using APY so compounding is already included:
- At the 0.37% national average: $10,000 × 0.0037 = $37
- At an example 3.50% high-yield rate: $10,000 × 0.035 = $350
That’s a $313 difference for doing nothing more than picking a better account. Over five years, that adds up to a nice chunk of extra cushion.
Watch out: A high-yield account at an online bank may take a business day or two to move money to your checking account. That’s fine for most emergencies. But keep a few hundred dollars in your regular checking or a linked savings account for same-day surprises, like a tow truck that wants payment on the spot.
Money market accounts vs. money market funds
These two sound alike, but they’re different products.
A money market deposit account is a bank account. It’s FDIC insured, just like savings (FDIC).
A money market fund is a type of mutual fund sold by brokerages. It holds very short-term debt and cash. According to the SEC’s Investor.gov, money market funds are not FDIC insured, and while they’re low risk, it’s possible to lose money in one (Investor.gov). Government money market funds, which invest at least 99.5% of their assets in cash, government securities and similar holdings, are the most conservative type. Some funds can also charge fees when lots of investors cash out at once.
Money market funds can be a reasonable home for a large emergency fund, especially if you already invest at a brokerage. Just know the trade-off: a little less protection in exchange for convenience and, often, a competitive yield.
CDs and Treasury bills: good for the back half
A certificate of deposit (CD) pays a set rate if you leave the money alone for a set time, like six months or a year. Pull it out early, and you usually pay a penalty. Treasury bills are short-term loans to the U.S. government that come due in a year or less.
Both can work for the “deep reserve” part of a large fund, the money you’d only need if a crisis lasted many months. Some people build a “ladder,” with CDs or T-bills coming due every few months so some cash is always about to free up. Just don’t lock up your starter fund this way.
A simple setup that works for most people
You don’t need to pick just one place. Many people use a simple two- or three-layer setup:
- Layer 1: A few hundred dollars in checking or a linked savings account at your everyday bank, for same-day needs.
- Layer 2: Your starter fund and most of your full fund in a high-yield savings account, reachable in a day or two.
- Layer 3 (optional): The deep reserve, money you’d only need many months into a crisis, in short-term CDs, Treasury bills or a government money market fund.
If that feels like too much to manage, skip Layer 3. One good high-yield savings account is plenty for most households.
Places to avoid
- The stock market. Stocks can drop sharply, and they often do in the same recessions that cause layoffs. You don’t want to sell low because your car broke down.
- Your retirement account. Pulling money from a 401(k) or IRA early can mean taxes, penalties and lost growth. It’s a last resort, not a plan.
- A big stash of cash at home. As the CFPB notes, “cash can be stolen, lost, or destroyed” (CFPB). A small amount for a power outage is fine.
How to build it, even on a tight budget
If saving feels impossible right now, you’re not alone. The trick is to make saving small, automatic and hard to undo. Here are the methods that work best.
1. Know where your money goes
You can’t save money you can’t find. If you don’t have a budget yet, our guide on how to make a budget that actually works walks you through it. Even one pass through last month’s spending often turns up money you didn’t realize was leaking out.
2. Open a separate account and give it a name
Open a savings account that’s just for emergencies. Many banks let you nickname accounts. Call it “Car Breaks Down” or “Job Loss Cushion.” Giving money a clear job makes it much easier to leave alone.
3. Automate it
Set up an automatic transfer from checking to savings on payday. The CFPB recommends this approach, and it suggests watching your checking balance so the transfers don’t cause overdraft fees (CFPB). If your employer allows it, you can also split your direct deposit so part of each paycheck goes straight into savings.
Start with whatever you can. Even $25 a week works.
Worked example 3: How long will it take?
Here’s how fast small amounts add up toward a $1,000 starter fund:
- $25 a week: $1,000 ÷ $25 = 40 weeks (about nine months)
- $50 a week: $1,000 ÷ $50 = 20 weeks (under five months)
Now let’s take Maria’s full goal of $9,840 for three months of essentials. If she saves $300 a month, it would take about 33 months ($9,840 ÷ $300 = 32.8). But if she also puts $1,200 from each yearly tax refund into the fund, she reaches her goal in about 25 months. That’s eight months sooner, just by saving windfalls.
4. Save your windfalls
Tax refunds, bonuses, cash gifts and rebates are some of the fastest ways to grow your fund. The CFPB points out that saving all or part of a tax refund could help you set up your fund quickly (CFPB).
The IRS makes this easy. With Form 8888, or the matching option in tax software, you can split your refund into up to three accounts (IRS). You could send part to checking and part straight to your emergency savings, so you never see it in your spending account.
5. Check whether your employer offers emergency savings
A newer workplace option is worth asking about. Since 2024, employers can offer a pension-linked emergency savings account, or PLESA, tied to their retirement plan. According to the U.S. Department of Labor, workers who aren’t highly paid can save up to $2,500 (adjusted for inflation over time) on an after-tax basis, and they must be allowed to withdraw at least once a month. The plan can’t charge fees just for your first four withdrawals each plan year (Department of Labor).
Not every employer offers one. But if yours does, it’s an easy way to save straight from your paycheck.
6. Grow your savings when your income grows
When you get a raise, send part of it to savings before you get used to spending it. Fidelity suggests this as a way to avoid “lifestyle creep,” where spending rises as fast as pay (Fidelity). The same goes for a paid-off loan. When a car payment ends, keep “paying” it, but to your savings account.
7. Find a few quick wins
- Cancel one or two subscriptions you rarely use, and move that amount to savings each month.
- Call your car insurance and phone companies once a year to ask for a better rate.
- Sell things you no longer use, like old phones, gear or furniture.
- Try a no-spend weekend once a month and save what you would have spent.
None of these will make you rich. But stacked together, they can fund your starter goal in a few months.
When to use it (and when not to)
Building the fund is half the battle. The other half is using it for the right things, and then refilling it.
The CFPB suggests setting clear rules ahead of time for what counts as an emergency (CFPB). Deciding when you’re calm is much easier than deciding when you’re stressed or tempted.
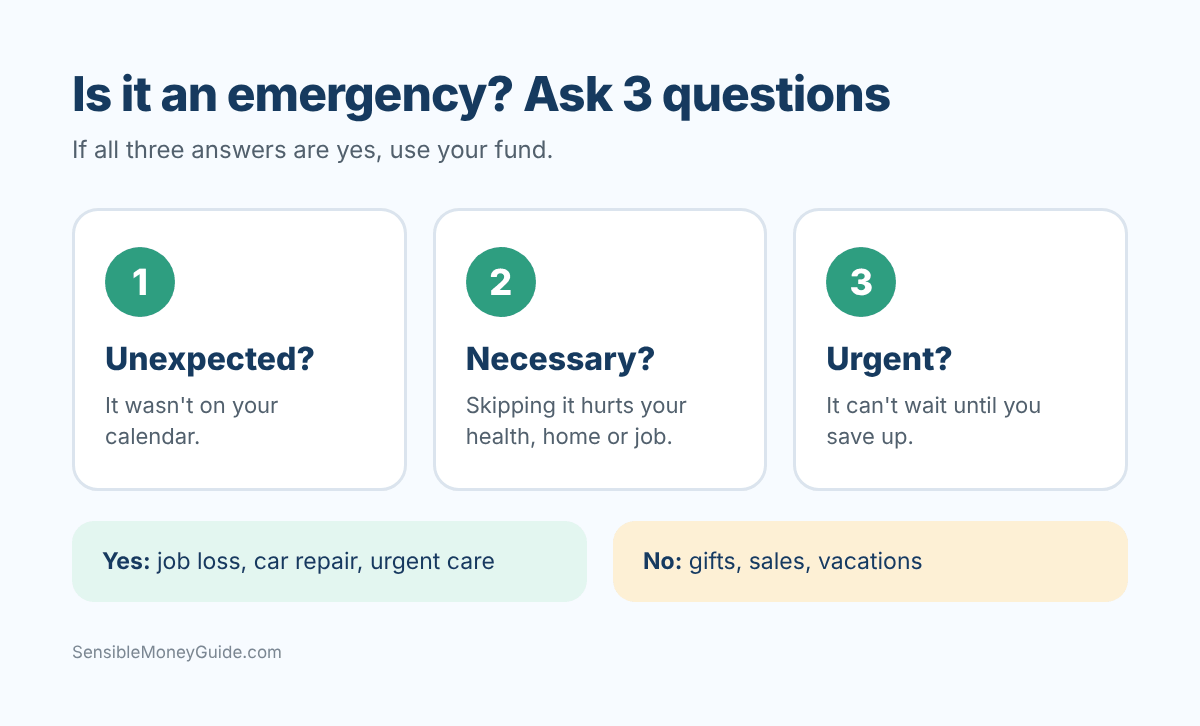
A simple three-question test
Before you tap your fund, ask yourself:
- Is it unexpected? A car repair is. Annual car registration isn’t, because it comes every year.
- Is it necessary? Would skipping it hurt your health, safety, income or housing?
- Is it urgent? Does it need to be paid now, or could it wait until you save for it?
If the answer to all three is yes, use the fund. That’s what it’s for.
Usually an emergency
- Job loss or a big, sudden cut in hours
- A car repair you need to get to work
- Urgent medical, dental or vet care
- A broken furnace, water heater or roof leak
- Last-minute travel for a family crisis
Usually not an emergency
- Holiday gifts, birthdays or back-to-school shopping (they come every year)
- A sale on something you want
- Vacation or concert tickets
- Planned home upgrades
- Regular bills you forgot to budget for
For predictable costs that don’t come monthly, like car registration or holiday gifts, set up a separate “sinking fund.” That’s a small savings bucket you add to every month for a known future cost. It keeps your emergency fund for true surprises.
Don’t be afraid to use it
Some people work so hard to build their fund that they can’t bring themselves to touch it. They put a $900 repair on a credit card “to protect the savings.” That defeats the purpose. The CFPB’s advice is plain: use the fund if you need it, then rebuild it (CFPB).
After you use it, go back to your automatic transfers, and point your next windfall at refilling it. In a February 2025 Bankrate survey, 37% of U.S. adults said they had used emergency savings in the past 12 months, so refilling is a normal part of the cycle (Bankrate).
Emergency fund or debt payoff first?
This is one of the most common money questions. If you have credit card debt, should every spare dollar go to the card? Or should some go to savings?
Bankrate found that 29% of U.S. adults have more credit card debt than emergency savings (Bankrate). So if this is you, you’ve got lots of company.
Why most experts say “a little of both”
Paying off a card with a 22% interest rate is a great “return” on your money. But if you put every dollar toward debt and have zero savings, the next surprise goes right back on the card. You can end up stuck in a loop.
That’s why many plans start with a small cash cushion, then attack debt hard, then finish the full fund. Ramsey Solutions’ Baby Steps follow this order: $1,000 starter fund, then pay off all non-mortgage debt, then build three to six months of expenses (Ramsey Solutions).
Others suggest working on both at the same time, such as sending most extra money to high-interest debt while still adding a small amount to savings each month. Both approaches can work. The key is to avoid zero savings while carrying high-interest debt.
Worked example 4: The real cost of using a credit card
Let’s say your car needs a $1,500 repair, and you have no savings. You put it on a credit card with a 22.15% APR, the recent average for accounts charged interest (Federal Reserve G.19). You pay $75 a month.
- Months to pay it off: about 26
- Interest paid: about $389
- Total cost of the repair: about $1,889
We figured this by adding one month of interest (22.15% ÷ 12) to the balance each month, then subtracting the $75 payment, until the balance hit zero.
Now picture the same repair paid from savings. It costs $1,500, and you rebuild the fund at $75 a month over 20 months. You save almost $400, and you avoid two years of card payments hanging over you.
Pro tip: If you have both debt and a 401(k) match at work, try to contribute at least enough to get the full match while you build your starter fund. A match is free money that’s hard to beat.
Common mistakes to avoid
1. Waiting until you can save “a real amount”
Many people put off saving until they get a raise or pay off a bill. But small amounts add up, and the habit matters more than the size. Start with $10 or $20 a week if that’s what you have.
2. Keeping it in checking
Money that sits next to your spending money tends to get spent. Keep your fund in a separate account, ideally at a different bank than your checking, so it takes a small step to move it.
3. Leaving it in a low-rate account for years
At a 0.37% average rate, a large fund barely grows. Inflation can shrink its buying power over time. A high-yield savings account can earn many times more with the same safety, as long as it’s FDIC or NCUA insured.
4. Investing it in stocks
It’s tempting to chase higher returns. But stock prices can fall sharply in a bad year, often at the same time that layoffs rise. Your emergency fund needs to be at full value when you need it.
5. Using it for things that aren’t emergencies
A great sale or a last-minute trip isn’t an emergency. Set up separate savings for planned costs so you’re not tempted.
6. Forgetting to refill it
Using your fund is fine. Leaving it empty afterward is the problem. Make refilling it your next money goal after any withdrawal.
7. Never updating your target
Your target should change when your life changes. A new baby, a move, a new car payment or a job change all affect how much you need. Check your number once a year.
Myths vs. facts
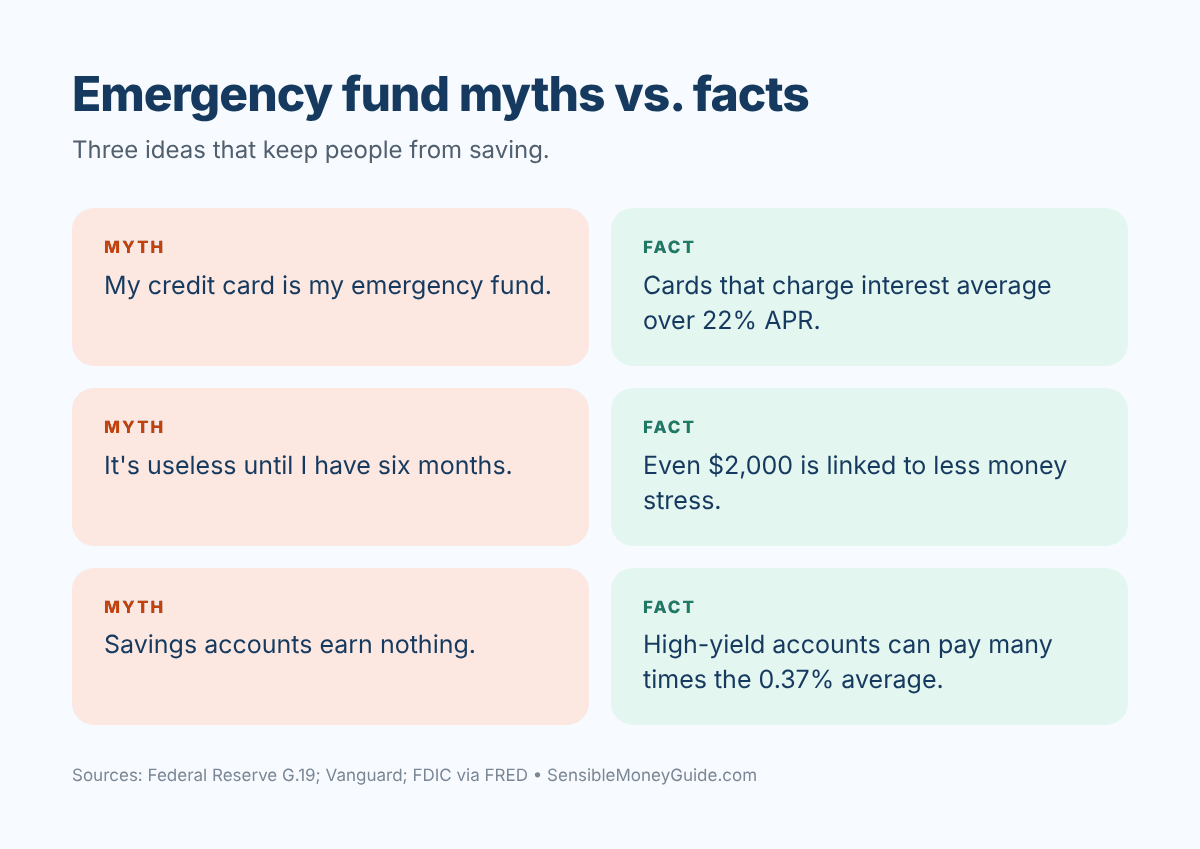
Myth: “I have credit cards, so I don’t need an emergency fund.”
Fact: A credit card is a loan, not savings. Card companies can lower your limit, and the average rate on cards charged interest was over 22% in mid-2026 (Federal Reserve G.19).
Myth: “An emergency fund is a waste because it earns almost nothing.”
Fact: High-yield savings accounts have recently paid several percent, far above the 0.37% national average (NerdWallet; FDIC national rate, via FRED). And the real return is avoiding high-interest debt and stress.
Myth: “I need six months saved before it does any good.”
Fact: Vanguard’s research linked having just $2,000 saved to a 21% higher sense of financial well-being (Vanguard). A small fund already helps.
Myth: “Money market funds are the same as bank accounts.”
Fact: Money market deposit accounts at banks are FDIC insured. Money market funds at brokerages are not, though they’re generally low risk (Investor.gov; FDIC).
Myth: “My 401(k) is my emergency fund.”
Fact: Early withdrawals can trigger taxes, penalties and lost growth. Keep retirement money for retirement.
Your step-by-step action plan
Here’s the whole guide boiled down into steps you can actually follow. Don’t try to do them all today. Just start with the first one.
- Add up your essentials. Use your last three months of statements to find your monthly must-pay costs.
- Set two goals. A starter goal of $500 to $2,000, and a full goal of three to six months of essentials.
- Open a separate, insured savings account. Look for a high-yield account with no monthly fees and FDIC or NCUA insurance.
- Name it. Give the account a nickname that reminds you why it exists.
- Automate a transfer. Set up a weekly or payday transfer, even if it’s just $20.
- Plan for windfalls. Decide now that part of your next tax refund, bonus or gift goes to the fund. Use Form 8888 to split your refund.
- Write your “what counts” rules. List what you’ll use the fund for, and what you won’t.
- Balance debt and savings. Once your starter fund is in place, send extra money to high-interest debt, then come back to finish your full fund.
- Refill after every use. Restart your transfers right away after a withdrawal.
- Review once a year. Update your target when your income, family or bills change.
Key takeaways
- An emergency fund is cash set aside only for surprise costs and income loss.
- Only 63% of U.S. adults would cover a $400 surprise with cash or its equivalent, according to the Federal Reserve.
- Start with a $500 to $2,000 starter fund. Vanguard’s research ties $2,000 in savings to much lower financial stress.
- Your full goal is usually three to six months of essential expenses, and more if your income is less steady.
- Keep it in an FDIC- or NCUA-insured high-yield savings account, separate from checking.
- Automate your savings and send windfalls like tax refunds straight to the fund.
- Use the fund for real emergencies without guilt, then refill it.
- If you have high-interest debt, build a starter fund first, then pay down debt.
Frequently asked questions
How much should I have in my emergency fund?
A common target is three to six months of essential expenses, like housing, food, insurance, transportation and minimum debt payments. If you’re just starting, aim for $500 to $2,000 first. Save more if you’re self-employed, the only earner, or work in a field with frequent layoffs.
Where is the best place to keep an emergency fund?
For most people, it’s a high-yield savings account at an FDIC-insured bank or NCUA-insured credit union. It’s safe, you can reach the money within a day or two, and it pays far more than the average savings account. Keep it separate from checking.
Is $1,000 enough for an emergency fund?
It’s a great starting point and covers many common surprises, like a car repair or urgent dental visit. But it won’t carry you through a job loss. Think of $1,000 as step one, then keep building toward three to six months of expenses.
Should I save or pay off debt first?
Most experts suggest doing both, in order. Build a small starter fund first so new surprises don’t go on a card. Then put extra money toward high-interest debt, and finish your full emergency fund after.
Should I invest my emergency fund?
Generally, no. Stocks can drop sharply, often at the same time that layoffs rise. Your emergency fund needs to be there at full value. A high-yield savings account, money market account or short-term CDs are safer choices.
How do I save an emergency fund on a low income?
Start small and automate it, even at $10 a week. Save part of every windfall, like tax refunds or gifts. Cut one or two expenses and move that money to savings. Small, steady amounts add up faster than you’d think.
What counts as an emergency?
An emergency is a cost that’s unexpected, necessary and urgent. Job loss, urgent medical care and a car repair you need to get to work all count. Holiday gifts, sales and vacations don’t, because they’re planned or optional.
Do I need an emergency fund if I have good credit?
Yes. Credit can be cut or reduced when you need it most, and borrowing costs interest. The average rate on credit card accounts charged interest was over 22% in mid-2026. Your own cash is cheaper and more reliable.
Your next step this week
Open a separate savings account this week, give it a name like “Emergency Fund,” and set up an automatic transfer of any amount, even $20, on your next payday. That’s it. Once the money starts moving on its own, you’ve done the hardest part.
Sources
- Federal Reserve Board: Economic Well-Being of U.S. Households in 2025. Accessed October 15, 2026.
- Federal Reserve Board: Report on the Economic Well-Being of U.S. Households: Unexpected expenses data. Accessed October 15, 2026.
- Federal Reserve Board: Report on the Economic Well-Being of U.S. Households: Emergency savings data. Accessed October 15, 2026.
- Federal Deposit Insurance Corporation (FDIC): Understanding Deposit Insurance. Accessed October 15, 2026.
- FDIC, via Federal Reserve Bank of St. Louis (FRED): National Rate: Savings (SNDR). Accessed October 15, 2026.
- National Credit Union Administration (NCUA): Share Insurance Coverage. Accessed October 15, 2026.
- U.S. Bureau of Labor Statistics: Employment Situation, Table A-12: Unemployed persons by duration of unemployment. Accessed October 15, 2026.
- Federal Reserve Board: Consumer Credit – G.19. Accessed October 15, 2026.
- Consumer Financial Protection Bureau (CFPB): An essential guide to building an emergency fund. Accessed October 15, 2026.
- U.S. Securities and Exchange Commission, Investor.gov: Money Market Funds: Investor Bulletin. Accessed October 15, 2026.
- Internal Revenue Service (IRS): Frequently asked questions about splitting federal income tax refunds. Accessed October 15, 2026.
- U.S. Department of Labor, EBSA: FAQs: Pension-Linked Emergency Savings Accounts. Accessed October 15, 2026.
- Vanguard: The relationship between emergency savings, financial well-being, and financial stress. Accessed October 15, 2026.
- Fidelity Investments: Guide to emergency savings. Accessed October 15, 2026.
- JPMorgan Chase Institute: Weathering Volatility 2.0: A Monthly Stress Test to Guide Savings. Accessed October 15, 2026.
- Bankrate: Bankrate’s 2026 Annual Emergency Savings Report. Accessed October 15, 2026.
- NerdWallet: Emergency Fund Calculator: How Much Will Protect You?. Accessed October 15, 2026.
- NerdWallet: Best High-Yield Savings Accounts of October 2026. Accessed October 15, 2026.
- Ramsey Solutions: The 7 Baby Steps. Accessed October 15, 2026.
- CNBC: Suze Orman explains how much money to keep in your emergency fund. Accessed October 15, 2026.
This article is for educational purposes only and isn’t financial advice. Consider talking with a qualified professional about your situation.

How to Save for a Down Payment: The Complete Guide

How to Lower Your Monthly Bills: The Complete Guide

How Federal Income Taxes Work: A Complete Beginner’s Guide

Roth vs. Traditional IRA: How to Choose the Right One

Index Funds Explained: A Complete Beginner’s Guide

How to Make a Budget That Actually Works: A Complete Guide

Emergency Fund Guide: How Much You Need and Where to Keep It

How Credit Scores Really Work: A Complete Guide
How to Lower Your Monthly Bills: The Complete Guide

How to Pay Off Credit Card Debt: The Complete Guide
-
 Budgeting1 week ago
How to Make a Budget That Actually Works: A Complete Guide
-
 Saving Strategies1 week ago
Emergency Fund Guide: How Much You Need and Where to Keep It
-
 Credit Management7 days ago
How Credit Scores Really Work: A Complete Guide
-
 Budgeting2 days ago
How to Lower Your Monthly Bills: The Complete Guide
-
 Debt Management6 days ago
How to Pay Off Credit Card Debt: The Complete Guide
-
 Investing Basics5 days ago
Index Funds Explained: A Complete Beginner’s Guide
-
 Retirement Planning4 days ago
Roth vs. Traditional IRA: How to Choose the Right One
-
 Tax Planning3 days ago
How Federal Income Taxes Work: A Complete Beginner’s Guide
You must be logged in to post a comment Login